

The AI revolution promises cheaper everything. But soaring electricity, chip, and construction costs tell a different story for inflation and markets.
KEY TAKEAWAYS
-
AI productivity gains are beginning to appear in economic data. Third-quarter productivity increased at a 3.6% annualized rate, while unit labor costs declined 0.7%, suggesting the economy may be producing more output at lower labor cost per unit.
-
The AI infrastructure boom requires extraordinary capital investment. Some Wall Street estimates project $1.66 trillion in AI-related capital spending next year, creating substantial demand for electricity, semiconductors, construction materials, and skilled labor.
-
Inflation remains a significant concern despite improving productivity. October consumer prices increased 0.4%, core inflation rose 0.3% for the third consecutive month, and electricity prices climbed 0.9%.
-
The Federal Reserve faces conflicting economic pressures. Higher interest rates may help contain inflation but also increase financing costs for the long-term infrastructure investments expected to generate future productivity gains.
-
The timing of AI's economic benefits matters enormously for investors. Elevated Treasury yields reduce the present value of distant corporate earnings, while higher interest rates increase the risks associated with long-duration bonds and heavily financed capital projects.
MY HOT TAKES
-
AI may ultimately be deflationary, but the road to that future could be surprisingly inflationary. Wall Street is celebrating tomorrow's productivity gains while consumers are already paying today's infrastructure bills.
-
The Fed may have to fight the very revolution it believes will transform the economy. Warsh's challenge is that containing today's inflation could require raising the cost of capital for the investments that might eventually solve it.
-
Investors are making the same mistake they made during the dot-com boom: confusing technological certainty with investment certainty. The internet delivered everything its advocates promised, but that did not prevent investors from losing enormous amounts of money along the way.
-
The AI trade is increasingly about distinguishing who collects the checks from who writes them. Infrastructure suppliers may benefit immediately from capital spending, while the companies financing the buildout must eventually demonstrate that their enormous investments generate acceptable returns.
-
Patience is no longer a zero-return investment strategy. With short-term Treasuries offering attractive yields, investors can afford to demand better valuations rather than paying premium prices for profits that may not materialize for years.
-
You can quote me: "The AI boom has two kinds of companies: those collecting checks for building the future and those writing the checks hoping the future eventually pays them back–investors had better know which ones they own."
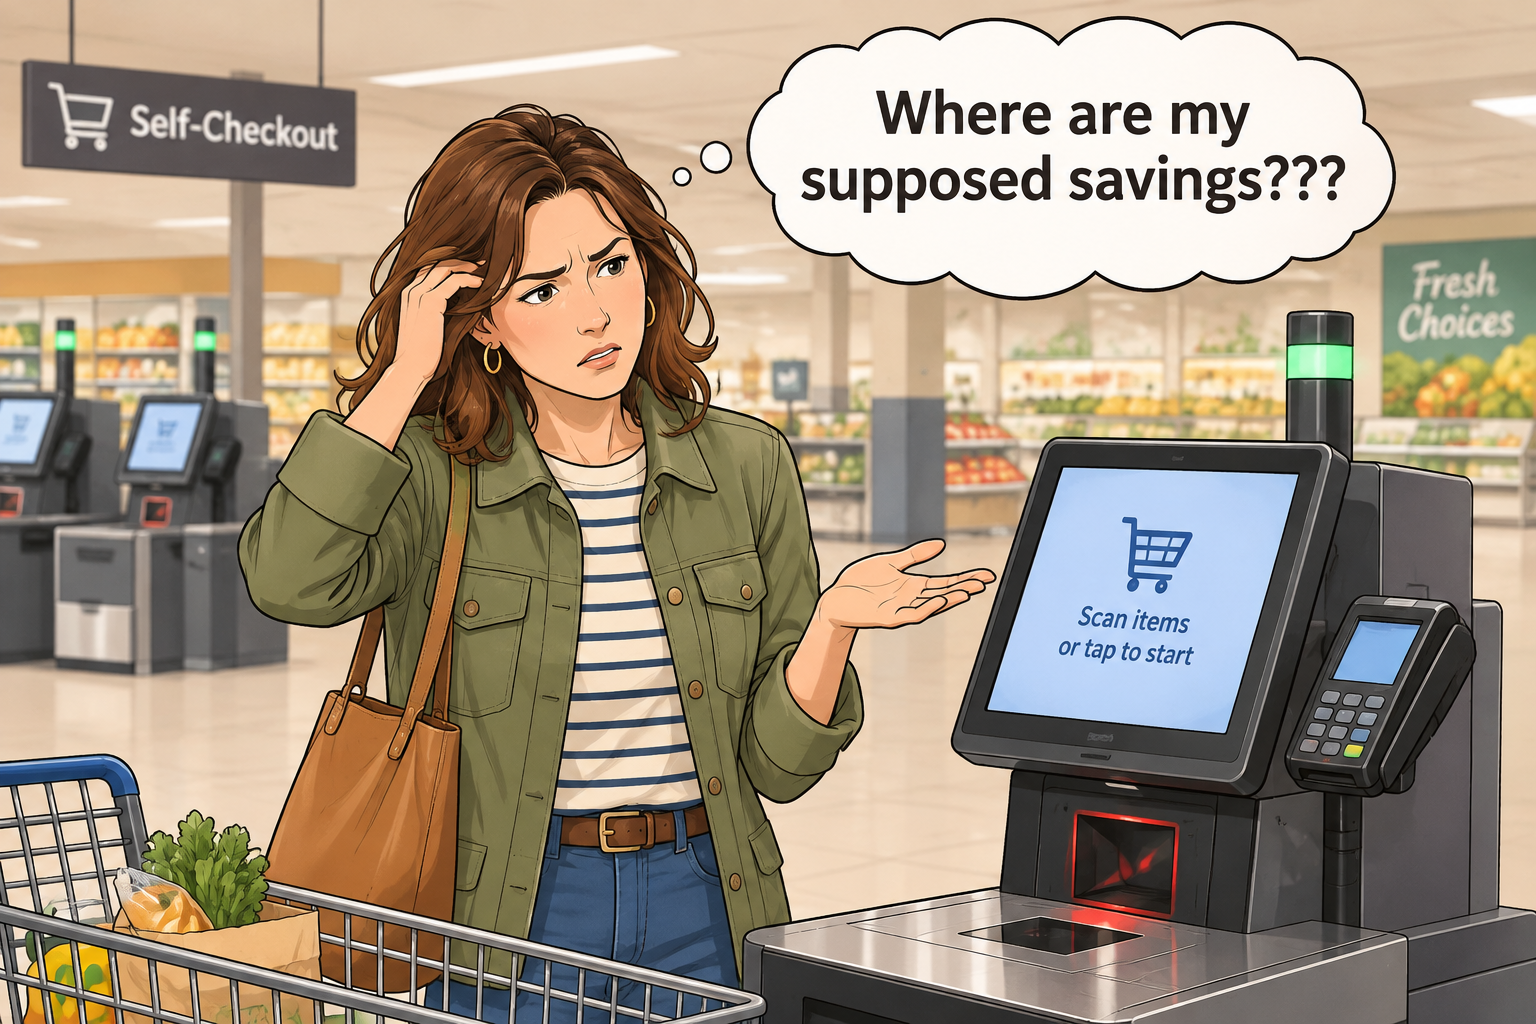
Unexpected item in the bagging area. 😠 If you have bought so much as a quart of milk in the last decade, you have been scolded by that voice. You know that I have an odd obsession with doing my own grocery shopping–I consider it field research–and a few years back, my store ripped out a row of checkout lanes and replaced them with self-checkout kiosks. I remember thinking, as any good finance guy would, fewer cashiers means lower costs, and lower costs mean…well, lower prices. Just kidding. 🤣 What actually happened is that I now scan my own tomatoes, bag my own tomatoes, get accused of stealing my own tomatoes by a machine–and pay MORE for them. The technology was supposed to make everything cheaper. Maybe someday it will. But somebody had to pay for those kiosks first, and I have a pretty good idea who it was. Hold that thought.
Today, at around noon Wall Street Time, Fed Chair Kevin Warsh walks into the San Francisco Fed to host a three-hour public forum on artificial intelligence. Three panels, with the Chair himself speaking before and after. You may recall that he set up five task forces when he took the job this past spring, and this is the ONLY public event scheduled for any of them. The one focused on AI is chaired by ubiquitous venture capitalist Marc Andreessen, and today’s guest list leans heavily toward Silicon Valley. In other words, the man who sets the price of money for the entire country is spending his Monday asking the tech industry what technology is going to do to the economy. I will let you decide what kind of answer you get when you ask a barber if you need a haircut.
Now, to be fair–and I always try to be–the Chair’s interest is not idle curiosity. Back in August at Jackson Hole, Warsh called this moment “a hinge point in history” and suggested that AI may be a brand-new factor of production, right alongside labor and capital. The theory goes like this. If AI allows workers to produce more in every hour they work (economists call that productivity), the economy can grow faster WITHOUT prices rising. Companies can pay people more without charging customers more. And if that is true, the Fed can leave interest rates lower than it otherwise would. That is the promise–growth without inflation–and it is a beautiful one.
And it is not a fantasy. Earlier this month, we learned that productivity grew at a 3.6% annual pace in the third quarter, and unit labor costs (what companies pay in wages for each unit of stuff they produce) actually FELL by 0.7%. Read that again. 👈👀 Output up, labor cost per unit down. If you are looking for early evidence that something good is happening under the hood of this economy, there it is.
So, case closed, right? The robots are coming, they are bringing lower prices with them, and the Fed can relax. UM...not so fast.
Before artificial intelligence can make a single thing cheaper, somebody has to BUILD it. Data centers the size of small towns. Chips by the millions. Power plants, transformers, and transmission lines to feed them all. Some Wall Street analysts expect AI-related companies to spend $1.66 trillion on capital projects next year–trillion, with a ‘T’–which would be 75% MORE than this year. That is not money sitting in a spreadsheet. That is $1.66 trillion chasing concrete, copper, electricians, memory chips, and electricity. Right now. In an economy that already has an inflation problem.
Do you want to see what that looks like in the data? One Wall Street estimate has the cost of memory chips on track to rise by more than 400% between the end of 2024 and the end of this year. Last Tuesday’s Consumer Price Index showed prices up 0.4% in October, more than expected, and core prices (leave out food and energy) up 0.3% for the THIRD straight month. Tucked inside that report was electricity, up 0.9% in a single month. You cannot plug in a continent’s worth of data centers without somebody’s power bill noticing–and that somebody is you. By one estimate, consumer prices have been rising at a 5.7% annual pace over the past three months. The payoff from AI is written in the future tense. The invoice is written in the present tense.
And here is the part I want you to underline. Nobody–not the Chair, not the venture capitalists on his panels, and certainly not me–can tell you WHEN the payoff arrives. It could be next year. It could be next decade. Productivity booms do not run on a schedule. Construction bills, on the other hand, come due every month. That gap between when you pay and when you benefit is the whole ballgame. It is where inflation lives, it is where the Fed lives, and–if you own stocks priced for the payoff–it is where your portfolio lives too.
Which brings me back to the Chair, and to what may be the most uncomfortable seat in San Francisco today. Warsh already raised interest rates in September–the Fed’s first hike since 2023. He held steady in October, but two of his colleagues dissented. The next decision comes on December 9, and futures markets have a hike priced as a near certainty, with roughly a one-in-ten chance that it is a half-point instead of the usual quarter. The 10-year Treasury yield closed Friday around 5.15%. Now think about what a rate hike actually does. It raises the cost of borrowing, and it lands hardest on big, expensive, debt-financed projects that will not pay off for years. Sound like anything we have been talking about? The Fed Chair who believes AI is a hinge point in history may have to raise the price of the very money that is building it. Hike too little, and the buildout keeps bidding up the price of everything it touches. Hike too much, and he risks choking off the very investment that is supposed to deliver the productivity he is counting on. Not exactly a comfortable choice. He believes in the destination. His job is to do something about the toll on the way there.
I have seen this movie before–from the inside. In 1999, I was at Lucent, and everybody in the building knew that the internet was going to make everything faster and cheaper. We were right! Alan Greenspan knew it too. He was famously patient through the mid-1990s precisely because he believed a productivity boom was underway. And then, starting in June of 1999, he raised interest rates six times in less than a year–from 4.75% all the way to 6.5%–finishing with a half-point hike in May of 2000. The productivity miracle was real. So was the hangover. Being right about the technology and being right about the timing turned out to be two VERY different trades.
So what does an investor do with all this? You know the drill–questions, not answers. Do you know which of your holdings SELL into the buildout and which ones PAY for it? Utilities, electrical-equipment makers, and chip suppliers sit on one side of that ledger. The companies writing the trillion-dollar checks–and every business that shares a power grid with them–sit on the other. If you own AI stocks, much of what you are paying for is profit that shows up years from now. With the 10-year above 5%, a dollar earned in 2031 is worth less today than it was when rates were lower. Has the price you paid caught up to that math? If you own bonds, how LONG are they? Longer-dated bonds are the most sensitive to rising rates (the Wall Street finance bros call that duration), and a Fed that is hiking into a building boom is not finished surprising people. And for my capital-preservation friends, a one-year Treasury bill currently pays north of 4.5%. You are being paid to be patient. What is your patience worth?
You won’t have to wait long for more clues. Nvidia–the biggest seller of picks and shovels in this particular gold rush–reports earnings tomorrow after the closing bell, and on Wednesday we get the minutes from the Fed’s October meeting, which should tell us just how many policymakers were itching to hike.
I will be listening to the Chair today. My guess is that his panelists will tell him that the future is bright, that the machines will make us all more productive, and that prices will eventually come down. And you know what? They are probably right. My grocery store was right too. Those kiosks ARE more efficient. The lines are shorter, and somewhere on a spreadsheet, the savings are very real. I am still paying more for tomatoes. So the next time somebody promises you that technology is about to make everything cheaper, believe them–and then ask who is paying for the kiosks in the meantime. Then take a good look at your own portfolio, because the machine has already spotted it. Unexpected item in the bagging area: a rate hike. 😉
FRIDAY’S MARKETS
Stocks finished mixed on Friday as chipmakers extended their slide, with Nvidia falling 2.0% a day after CEO Jensen Huang resigned and Advanced Micro Devices dropping 8.8%. The S&P 500 fell 0.40%, the Nasdaq Composite lost 0.91%, the Russell 2000 slipped 0.31%, and the Dow Jones Industrial Average gained 50 points to 52,348, with the S&P 500 and Nasdaq still posting their first weekly gains in five weeks. The 10-year Treasury yield ended around 5.15% and the 2-year near 4.87% after the October Producer Price Index rose 0.3% for the month, less than expected, and 6.5% from a year earlier. Brent crude settled up 2 cents at $95.84 and WTI slipped 0.2% to $88.56, while bitcoin fell below $70,000 for the first time since August.
NEXT UP
-
Empire Manufacturing (November) is expected to have slipped to 18.0 from 25.5.
-
Fed speakers today: Barr, Williams, and Hammack. The main event is Chairman Warsh speaking at a productivity conference in San Francisco–maybe he will answer the questions in this morning’s blogpost. 🙃😉
-
Important earnings today: Tyson Foods and Aramark.
-
Tune into Yahoo!Finance’s Market Hang at 12:30 Wall Street Time today and throughout the week where I will be hosting an hour-long discussion with some of Wall Street’s brightest. On tap: everything you want to know about…well, everything important to your portfolio. 👉https://finance.yahoo.com/videos/series/market-hang/
 service@siebert.com
 Siebert Financial (800)872-0444