
The consumer says one thing and spends another. Why conflicting confidence surveys, rising prices, and declining saving rates demand a closer look.
KEY TAKEAWAYS
-
Consumer confidence surveys delivered conflicting signals in October. The University of Michigan's Consumer Sentiment Index slipped to 48.0 from 48.1 in September, while the Conference Board's Consumer Confidence Index climbed 7.5 points to 91.7.
-
Consumers remain concerned about affordability and major purchases. Michigan's current conditions index fell to 46.7, with buying conditions for durable goods plunging 18%, while the Conference Board's Expectations Index remained below the recession-warning threshold of 80.
-
September retail sales increased 0.8%, but gasoline accounted for a substantial portion of the gain. Excluding gas stations, sales increased just 0.2%, a change the Census Bureau reported as statistically indistinguishable from zero.
-
Rising prices are complicating the interpretation of consumer spending. Gas station sales increased 28.1% year over year against a 34.2% increase in gasoline prices, while grocery store sales rose 0.9% against a 1.8% increase in food-at-home prices.
-
Household spending continued to outpace income growth in August. Personal spending increased 0.9% against income growth of 0.2%, while the personal saving rate declined to 4.1% from 4.6% in July.
MY HOT TAKES
-
Consumer confidence surveys tell me how Americans feel, but household finances tell me what they can afford. When sentiment indicators disagree, I put more weight on real purchasing power, income growth, and the saving rate.
-
Higher retail sales do not automatically mean a healthier consumer. If Americans are spending more dollars to purchase fewer goods, revenue growth may be masking declining purchasing power rather than signaling genuine strength.
-
Lower gasoline prices may provide temporary relief, but they do not resolve the underlying affordability problem. Rising diesel costs threaten to push transportation expenses back into the prices consumers pay for everyday necessities.
-
The K-shaped consumer economy is becoming increasingly important for investors. Strong restaurant spending can coexist with struggling grocery shoppers, making a company's customer demographics just as important as its headline revenue growth.
-
A strong GDP number will not convince me that consumers are financially healthy if spending continues to outpace income. The personal saving rate may be the most revealing number in tomorrow's economic releases because it shows whether households are sustaining consumption by drawing down their reserves.
-
You can quote me: "The households with cushions are still dining, while the households without them are trading down in the cereal aisle."
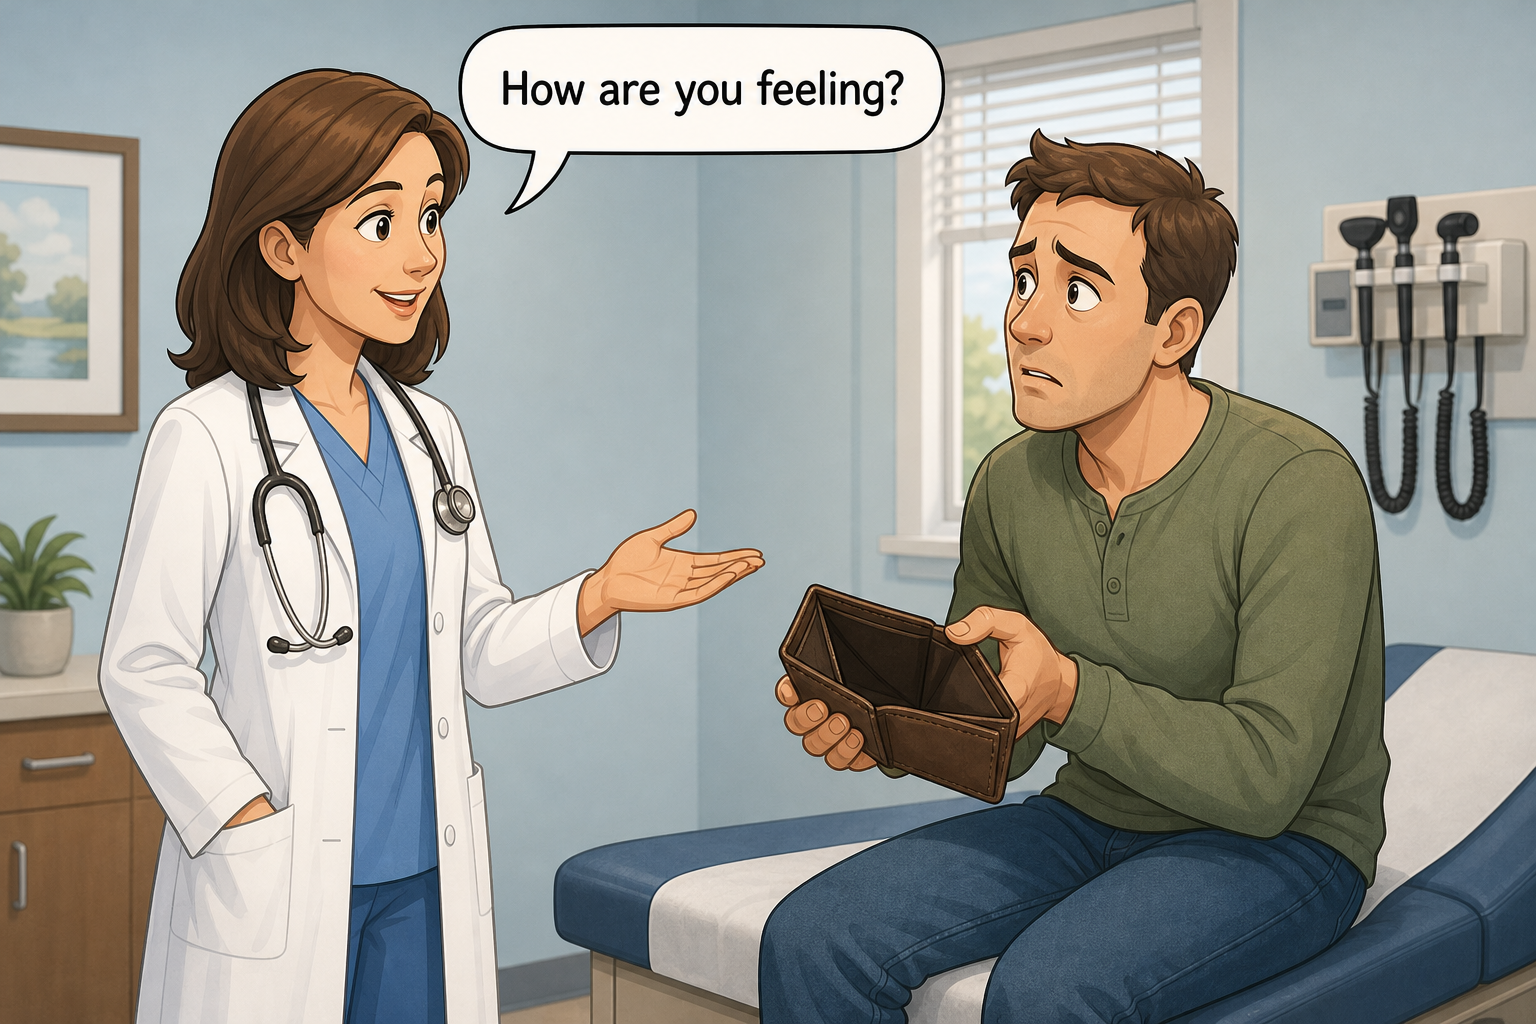
Not that kind of Doctor. Every year at my physical, my doctor opens with the same question–"So, how are you feeling, Mark?"–and every year I give her the same answer. "Great! Never better." She nods politely, writes absolutely nothing down, and swivels her chair toward the screen with my bloodwork on it. It took me a few years to understand that my answer is not data. It is a mood. I might have slept badly, I might have downed a double espresso or two on the way in (guilty), or I might simply be a media-trained Wall Streeter who answers every question with total confidence. The bloodwork doesn't care how I feel. Cholesterol, blood sugar, that long column of numbers with the little arrows next to them–THOSE are what she actually reads. Over the years I have noticed something else. The visits where I feel lousy and the labs come back clean are a relief. The visits that worry me are the opposite–when I feel fine and one of those numbers quietly drifts out of range. Nobody feels high cholesterol. That is exactly what makes it dangerous.
I have been thinking about that swivel chair all week, because the American consumer just had two checkups, and the patient gave two completely different answers to "how are you feeling?" Last Friday, the University of Michigan reported its final consumer sentiment reading for October at 48.0, a hair below September's 48.1 and well below the 53.6 of a year ago. Then yesterday, the Conference Board's Consumer Confidence Index jumped 7.5 points to 91.7, up from 84.2 in September. Same month, same country, same shoppers–opposite moods. And all the while, Americans keep spending. So which is it? Do we believe what the patient SAYS, or what the patient DOES? My answer is neither–not yet, anyway. We read the labs.
Start with how the patient feels, because the fine print is more useful than the headline. The Michigan survey's current conditions index fell to 46.7 from 50.9, and the entire decline came from buying conditions for durables (big-ticket items meant to last, like cars, appliances and furniture–or what I always jokingly refer to as things that hurt if you drop them on your toe), which plunged 18% on higher interest rates and affordability worries. The share of consumers who volunteered–unprompted–that “high prices are dragging down their personal finances” rose for a fourth straight month to 56%, up from 45% in January. Sentiment now sits 15% below where it stood in February, just before the Iran conflict began. And the Conference Board's bounce? Look closer. Its own economist tied the rebound to gasoline prices easing from September to October, and noted that consumers actually planned to spend LESS on services and durable goods over the next six months. The Expectations Index (the forward-looking part of the survey) rose to 72.6, but that only partly reverses three straight monthly declines and leaves it below 80–the level the Conference Board has long said typically signals a recession ahead. Consumers still expect prices to rise 5.8% over the next year. A patient who feels a little better because the painkiller kicked in is not a patient who is cured.
Now the vitals. On the surface, September's retail sales report looked perfectly healthy. Sales rose 0.8% to $745.0 billion, up 6.3% from a year earlier. Healthy, right? Not so fast. Retail sales are measured in dollars, not in things (the report is not adjusted for inflation), so a store selling the same number of items at higher prices looks like it is growing. Strip out gas stations and sales rose just 0.2%–and the Census Bureau marks that number with an asterisk, meaning it cannot statistically tell it apart from zero. Zero! Gas station sales, meanwhile, jumped 6.4% in a single month and 28.1% from a year ago. Here is the number I keep circling in red ink. The Bureau of Labor Statistics says gasoline prices rose 34.2% over the twelve months ending in September. If the price at the pump rose 34% and spending at the pump rose 28%, Americans are paying more–and pumping LESS. It is rough math (gas station sales include the coffee and snacks inside), but the direction is hard to miss. The same thing is happening in the grocery aisle. Grocery store sales rose 0.9% from a year ago while food-at-home prices rose 1.8%. More dollars, fewer items in the cart. That is not a consumer on a shopping spree. That is a consumer paying a toll.
So how does anyone keep paying more for less? The last full lab panel we have is from August–and I want to be clear that it is about to be updated. The Bureau of Economic Analysis (BEA) reported that spending rose 0.9% in August while income rose just 0.2%, and after inflation, disposable income (what is left after taxes) did not grow at all–as in 0.0%. The personal saving rate (the share of after-tax income households set aside) fell to 4.1% from 4.6% in July. The New York Fed's most recent household debt report showed credit card balances climbing $21 billion in the second quarter to $1.263 trillion, with 6.97% of card balances moving into serious delinquency over the past year, a touch above 6.93% the year before. To be fair–and I want to be fair–the New York Fed also said delinquency rates across most products have held steady for two years. This is not a patient in the emergency room. It is a patient whose savings account has quietly started paying for the groceries.
There is one more result on the chart that should matter to many of my long-time followers. The Conference Board found that confidence among Gen X, Baby Boomers and the Silent Generation continues to trail well behind Gen Z and Millennials–a generational divide that has widened over the past two years. On a six-month average, only consumers under 35 and households earning $100,000 or more reported rising confidence. If you are retired, or within shouting distance of it, you are not imagining things. A fixed income does not stretch the way a paycheck does when the price of everything keeps moving. And while gasoline has eased–the national average for regular was $4.27 on Monday, down from $4.48 in late September–diesel is moving the other way, rising to $6.35 from $6.18 just two weeks earlier. Diesel moves the trucks. The trucks move the groceries. You can do the rest of the math. 🤮
For investors, this is where it gets practical. Earnings season is in full swing, and every retailer that reports will tell you about "sales growth." Ask how much of it is volume and how much is price. A company growing revenue by selling fewer items at higher prices is telling a very different story than one selling more items–even if the top line looks identical. Ask who is absorbing higher freight and diesel costs–the company's margins or the shopper's wallet. And do not mistake every bright spot for a broad recovery. Restaurant and bar sales rose 7.0% from a year ago in September, well ahead of the 3.5% rise in menu prices–so somebody is still eating out, and eating out a lot. That is the K-shape in a single line item. The households with cushions are still dining, while the households without them are trading down in the cereal aisle. Know which customer the company you own actually serves. And with consumers telling both surveys they plan to pull back on big-ticket purchases, ask whether the companies selling those items are priced for a customer who may not show up this holiday season.
Which brings me back to the doctor's office–because the real lab results come in tomorrow morning. At 8:30 AM Wall Street Time on Thursday, the BEA will release September personal income and spending AND its first estimate of third-quarter GDP–at the same time. The Atlanta Fed's GDPNow model put third-quarter growth at 3.5% as of its October 20 update. That headline may look robust. But I will not be staring at the headline. I will be staring at the saving rate. If September's spending was once again paid for by saving less, the patient is running on reserves, and reserves–unlike moods–run out. And this afternoon at 2 PM, the Fed announces its rate decision, a reminder that the medicine for inflation is the same medicine that makes the credit card bill…well, more expensive.
So, how is the American consumer feeling? Depends on who you ask, and on which day you ask. But that was never the right question, and my doctor knew it long before I did. At my next physical I fully intend to tell her I feel GREAT–I always do–and then sneak a peek at the screen before she swivels around. The consumer will keep telling the pollsters it feels miserable and keep handing over the card at the register. "I feel fine." Sure you do. The labs come back at 8:30.
YESTERDAY’S MARKETS
Stocks closed higher on Tuesday as chipmakers rallied on the first day of the Fed’s two-day meeting, with the Dow Jones Industrial Average edging up 16 points to 52,378, the S&P 500 gaining 0.60% and the Nasdaq Composite climbing 1.18%. Technology was the best-performing sector at 1.5%, while energy was the weakest as West Texas Intermediate crude fell 1.83% to settle at $99.90 a barrel. Boeing tumbled 10.7% after reporting a wider-than-expected third-quarter loss, while UPS rose 5.8% after beating estimates and raising its full-year outlook. AMD gained 5.5% and Broadcom added 4.0%.
NEXT UP
-
At 2:00 PM Wall Street Time, the Fed’s FOMC will announce its rate decision. It is largely expected to hold rates steady. The Chair will hold a presser at 2:30, which is where the action–if any 😉–will be. Tune in regardless, because it will affect your money!
-
Important earnings today: Vertiv, Amphenol, Phillips 66, Jersey Mike’s, Generac, VF Corp, Biogen, GE Vernova, NiSource, Boston Scientific, Lennox, Evercore, American Electric Power, Oris Worldwide, Etsy, Flex, International Paper, ADP, Wingstop, Align Technology, T-Mobile, Ford, Chipotle, MGM Resorts, FedEx, American Water Works, Alphabet, ServiceNow, Microsoft, Honeywell Aerospace, VICI Properties, Carvana, Tenable, eBay, Fortinet, Sprouts Farmers Market, and O’Reilly Automotive.
 service@siebert.com
 Siebert Financial (800)872-0444