

PMI data points to powerful economic growth, but the bond market is demanding higher rates and changing the valuation equation for stocks.
KEY TAKEAWAYS
The economy is accelerating sharply. The flash composite PMI rose to 58.4, with both manufacturing and services reaching multi-year highs.
The bond market treated the strong data as an inflation and rate risk. The 10-year Treasury yield jumped to 5.10% while the 2-year climbed to 4.89%.
Capacity pressures are beginning to emerge. Backlogs, supplier delays, hiring and difficulty finding workers all suggest demand may be pressing against the economy's ability to supply it.
Higher yields are changing the valuation equation for stocks. Strong earnings support the numerator, but a rising risk-free rate puts increasing pressure on the denominator.
Stocks are offering almost no earnings-yield advantage over Treasuries. With an S&P 500 earnings yield around 5.15% and the 10-year near 5.10%, investors are being compensated very little for taking equity risk.
MY HOT TAKES
The biggest market risk right now may not be weak growth but excessive heat. Strong economic activity is welcome, but it makes the Fed's inflation problem considerably harder.
The Treasury market deserves more attention than the stock market right now. Rising yields and weak auction demand may reveal changing investor behavior before equities fully adjust.
The equity market can handle higher rates if earnings continue delivering. What becomes dangerous is a market that needs both strong earnings growth and continued multiple expansion.
Investors may own more duration than they realize. Expensive growth stocks with profits far into the future can react to rising interest rates much like long-duration bonds.
Cash and short-term Treasuries have become legitimate portfolio competitors again. When investors can earn close to 5% without taking equity risk, every risky asset must clear a much higher hurdle.
You can quote me: “Businesses are cooking. Households are sweating.”
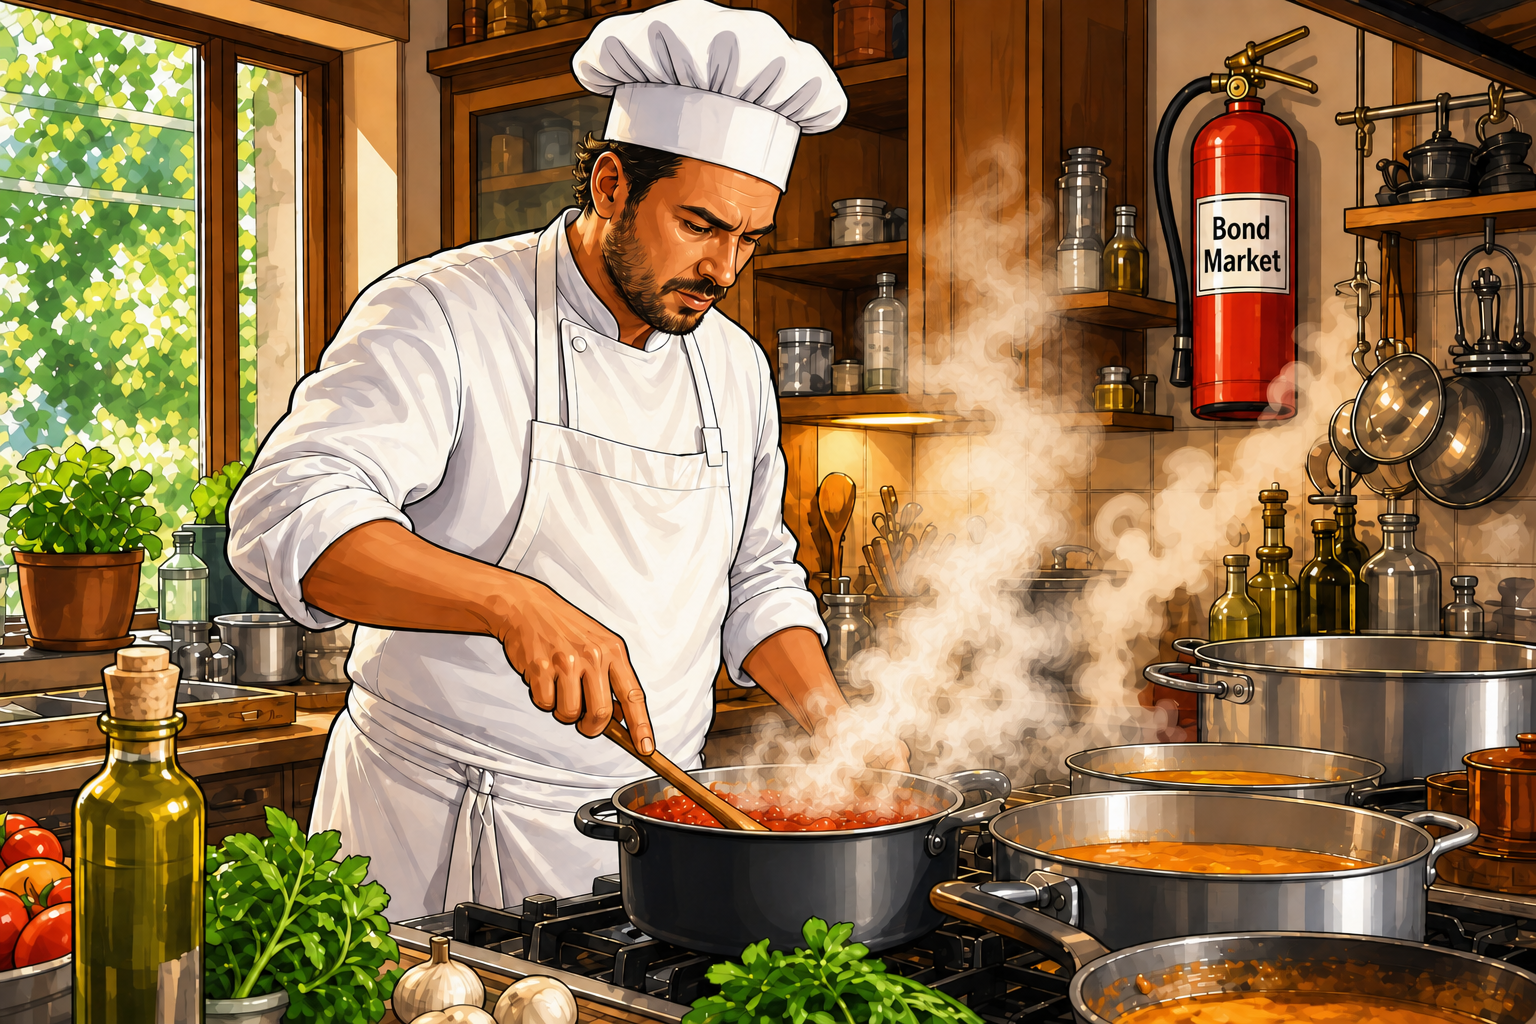
Al dente. I consider myself a pretty good cook–my family might choose a different adjective, but I'll take it. 😉 And every cook learns the same lesson the hard way. Heat is your best friend right up until the moment it becomes your worst enemy. A sauce NEEDS heat–to reduce, to thicken, to come alive. Leave the burner on high for two minutes too long, though, and you may find yourself scraping that perfectly pungent Puttanesca off the bottom of the pan and ordering in. 🤣 The trick isn't avoiding heat. It's knowing when to turn it down.
Yesterday, the people who run America's factories and service businesses told us…well, that the burner is on HIGH. The economy is cooking at its fastest pace in more than five years. That sounds like great news–and in a lot of ways, it is. But the bond market leaned over the stove, sniffed, and asked the question every cook dreads…is something starting to burn?
Let's start with what's on the stove. Yesterday's flash PMI (the Purchasing Managers' Index–a monthly survey asking the people who buy supplies for businesses whether things are getting better or worse–I like to refer to it as ‘corporate sentiment’) came in HOT. The composite reading jumped to 58.4 from 56.0 in August–a 62-month high and the fastest expansion since July 2021. Anything above 50 means growth. Anything above 58 means somebody cranked the knob. Manufacturing jumped to 57.0 from 53.9, a 52-month high, and services climbed to 58.7, a 59-month high. The economists who compile the survey estimate it points to annualized growth of around 5%–with roughly 4% for the third quarter as a whole. Setting aside the post-lockdown reopening frenzy, it's the biggest improvement in business activity since early 2015. Early 2015–my friends–that is more than a decade ago!
But alas, the bond market didn't celebrate. It flinched. The 10-year Treasury yield jumped more than 13 basis points to 5.10%–its highest level since July 2007. The 2-year yield, the maturity most sensitive to what the Fed does next, climbed to 4.89%, its highest since May 2024. And the PMI wasn't the only thing turning up the flame. Brent crude jumped nearly 4% to settle above $103 a barrel. A Fed governor said more hikes are needed to tame sticky inflation. Then came what I thought was the most telling moment of the day–a 5-year Treasury note auction that went poorly. The government had to pay 5.033% to sell the notes, far above the 4.19% average of the previous six auctions, and indirect bidders (a group that includes foreign central banks) took just 54% of the sale versus 65%, which is the norm. When the world's largest borrower has to raise its price to find buyers you MUST pay attention. Yields don't only rise because the Fed says so. They rise when lenders demand more to lend–and every mortgage, corporate bond and small-business loan in America is ultimately priced off that same benchmark. Growth, oil, a hawkish Fed and reluctant buyers. Four burners, all on high, all at once.
So is the economy heating up? By this survey, unmistakably YES. But I want to be careful here, because I've been doing this long enough to know that a survey is not a GDP report. The PMI is what's called a diffusion index. It tells you how MANY companies say business is improving–not how MUCH it is improving. The flash reading is built on roughly 80% to 90% of responses and gets finalized in early October. And if you read the fine print, the heat isn't evenly spread. Demand is coming almost entirely from home–goods exports are still falling. Service companies, despite booming activity, remain gloomier than usual about the year ahead, citing the cost of living, higher borrowing costs and political uncertainty. Tomorrow's final consumer sentiment reading is expected to sit near 47.8–a number that sounds more like a recession than a boom. Businesses are cooking. Households are sweating. That's the K-shaped economy served up in a single week of data.
Here's the part that worries me–and it isn't the growth. Growth is good. What matters is what happens when growth runs out of room, and you can only fit so many pots on one stove. Backlogs of unfinished orders rose at the sharpest rate since May 2022. Supplier delays were the most widespread since July 2022. Companies hired at the fastest pace since June 2022–a pace rarely exceeded since the data began in 2009–and they are STILL reporting trouble finding qualified staff. That isn't an economy warming up. That's an economy bumping into the walls of its kitchen. And when demand outruns capacity, companies discover something wonderful for them and dreadful for the Fed–pricing power. Input costs jumped at the steepest rate in four years, led by fuel and transport. To be fair, selling prices, while rising faster than in August, are still climbing more slowly than they did from March through July. Pricing power is building. It isn't running wild. Yet. But the Fed doesn't get paid to wait for "yet." Futures markets now price somewhere around a 70% chance of another rate hike on October 28–up from less than 10% just a month ago.
Which brings me to the question I get asked more than any other on days like this. Isn't a booming economy GOOD for stocks? Yes–and no. A stock's value really comes down to two things: the earnings a company generates, and the rate used to discount those future earnings back to today's dollars–yes, it’s that simple. A hot economy helps the first. It hurts the second. The earnings side looks terrific. Consensus estimates call for S&P 500 earnings growth of roughly 32% this year and about 15% next year. That's the numerator, and it's a beauty. The problem is the denominator. When the risk-free rate jumps, every future dollar of profit is worth less today. And the further out those profits sit, the bigger the haircut–which is why the market's long-dated growth darlings tend to feel rising yields first, and feel them most. You saw it yesterday. The S&P 500 fell 0.75%, the tech-heavy Nasdaq Composite dropped 1.13%, and utilities and consumer discretionary led the way down–precisely the sectors most sensitive to interest rates and to a squeezed consumer.
Now here's a number I haven't seen in many headlines. Take the S&P 500's expected earnings over the next twelve months and divide them by the index price. You get what's called the earnings yield–essentially the "interest rate" the stock market pays you for owning it. At yesterday's close, it works out to roughly 5.15%. The 10-year Treasury pays 5.10%. Let that sink in. Investors are being paid about FIVE basis points–five one-hundredths of a percentage point–to own stocks instead of a bond backed by the U.S. government. I'll admit the comparison isn't perfect. Company earnings can grow over time, and a bond's coupon never does. But that gap is supposed to be your reward for taking risk. Right now, it is all but gone.
So what does this mean for you? I'm not suggesting anyone run for the exits. A strong economy with rising earnings is a far better problem to have than a recession. But it is worth asking yourself a few honest questions. Is your portfolio counting on earnings growth–or on stocks getting more expensive? Only one of those tends to work when rates are rising. How much "duration" do you really own? Long-term bonds aren't the only rate-sensitive assets–high-flying growth stocks whose biggest profits are years away can behave a lot like 30-year bonds. Do the companies you own HAVE pricing power, or are they the ones paying for it? With the 2-year Treasury yielding close to 4.9%, what is the real cost of keeping some powder dry while the Fed decides how hot is too hot? And if this year's rally has left you heavier in exactly the assets that suffer when the denominator rises, is now the time to consider a rebalance?
Here's the interesting twist–yesterday's news was GOOD. The economy is strong, companies are hiring, and orders are pouring in. It's just that good news isn't free anymore. When stocks already assume everything goes right and bonds finally demand to be paid for the risk, even a booming economy can leave investors with a bill. And the bond market, as usual, is the one holding the check.
Back in my kitchen, nobody turns off the stove just because the sauce is bubbling–that's how you end up with a cold dinner. You turn it down. You stir. You pay attention. The economy is percolating away–bubbling beautifully right now, and I'm genuinely glad about that. The question is whether the Fed can find "simmer" before the bottom of the pan scorches–and whether investors are standing close enough to the stove to notice when it does. Me? I'll be the one hovering over the burner with a wooden spoon. 😉🍝
YESTERDAY’S MARKETS
Stocks fell yesterday, with the S&P 500 down 0.75%, the Dow Jones Industrial Average down 352 points, or 0.68%, to 51,511, and the Nasdaq Composite down 1.13%. Utilities and consumer discretionary led the decline, each falling more than 1%. The 10-year Treasury yield rose more than 13 basis points to 5.10%, its highest level since July 2007, while the 2-year yield climbed to 4.89%, its highest since May 2024. Brent crude rose 3.86% to $103.08 a barrel, and WTI crude gained 1.81% to $92.16.
NEXT UP
Initial Jobless Claims (September 19th) is expected to come in at 200k, slightly higher than last week's 196k claims.
New Home Sales (August) may have risen by 1.2% after falling by -10.3% in July.
Fed speakers today: Williams, Barkin, Hammack, and Paulson.
And don’t miss the Trump - Xi meeting today–it could move markets 😉
The Treasury is going to auction $44 billion 7-year Notes today. Let’s see if it is a repeat from yesterday’s lethargic 5-year auction.
 service@siebert.com
 Siebert Financial (800)872-0444