
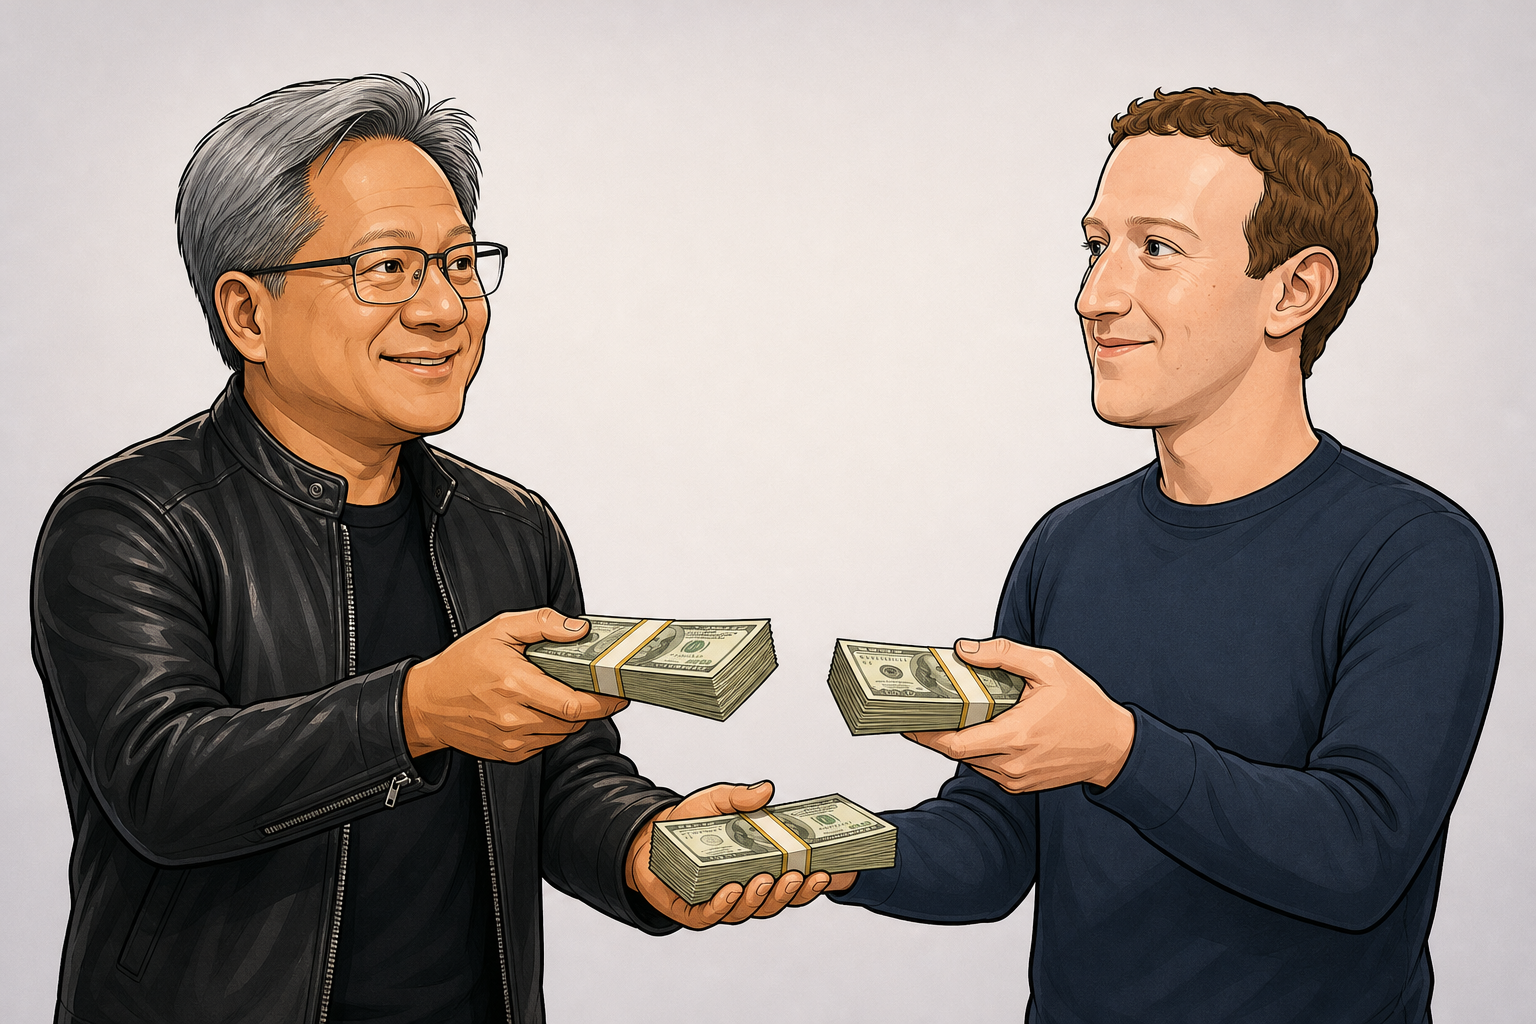
Meta is raising billions as NVIDIA invests in its customer. The real question for AI investors: how much chip demand is organic, and how much is financed?
KEY TAKEAWAYS
-
Meta announced a $97.5 billion equity fundraising plan. The package includes $25 billion in common stock, $12.5 billion in depositary shares, and up to $60 billion in future non-voting Class C shares expected to begin trading in early 2027.
-
NVIDIA is investing $3 billion in Meta as part of an expanded AI partnership. NVIDIA, AMD, and Broadcom have collectively expressed interest in purchasing up to $5 billion of Meta's Class A shares.
-
Meta reported negative free cash flow of $2.12 billion in the third quarter, compared with positive $10.63 billion a year earlier. Its 2026 capital expenditure guidance stands at $135 billion to $145 billion, alongside approximately $825 billion in future spending commitments.
-
Meta held $82.45 billion in cash and marketable securities against $80.92 billion in long-term debt at the end of September. The company has also accessed the bond market and secured a $27 billion data center financing arrangement involving Blue Owl.
-
Lucent's late-1990s vendor-financing arrangements offer a historical comparison. By mid-2000, Lucent had approximately $7.7 billion in customer credit commitments and another $1 billion in debt guarantees, before customer Winstar filed for bankruptcy in April 2001.
MY HOT TAKES
-
The biggest risk in AI isn't necessarily that the spending stops—it's that investors misunderstand what's keeping it going. When suppliers finance their customers, reported demand becomes a less reliable measure of independent market appetite.
-
Meta isn't running out of money, but its financing strategy is changing dramatically. A company that once funded enormous investments from operating cash flow is now leaning on bonds, private credit, and equity to keep building.
-
NVIDIA investing in its own customers isn't inherently problematic, but it creates a potentially dangerous feedback loop. When the companies selling the equipment help finance the purchases, investors need to distinguish organic demand from capital-supported demand.
-
The comparison between Meta and Winstar isn't about predicting another bankruptcy. It's about recognizing a financing structure that can make an investment boom appear stronger and more sustainable than it might otherwise be.
-
Meta's proposed $60 billion non-voting share issuance raises questions about dilution and shareholder influence. Investors are being asked to provide enormous amounts of capital for an AI strategy whose ultimate returns remain uncertain, without receiving additional voting power.
-
You can quote me: "The risk is not that Meta goes broke. The risk is that the AI trade is starting to grade its own homework."
We’re gonna need a bigger lucite. For a few years around the turn of the century, I had a problem that most people on Wall Street would happily trade for–I ran out of desk. Not office space, not shelf space–DESK. During my years working on M&A at Lucent, the deals came so fast that the deal toys (as we call them on Wall Street), or lucites, piled up faster than I could find places to put them. If you have never held one, a deal tombstone (a block of clear acrylic with a miniature of the deal announcement or a related object sealed inside) is Wall Street's version of a participation trophy, except that everyone listed actually participated–the buyer, the seller, the bankers, the lawyers and, in those days, almost always–the lenders. Every closing produced one. They lined the windowsill, then the top of the filing cabinet, then every inch of the desk's edge, until one day I swept the whole collection into a cardboard box that lived under my desk for longer than I care to admit. Every so often I would fish one out–they make excellent paperweights and terrible coasters–and read the fine print. That is the thing about a tombstone. The big type tells you who did the deal. The fine print tells you who made it possible.
I thought about that box yesterday when Meta announced what has grown, as of this morning, into a $97.5 billion equity fundraising–the largest in the company's history. The mechanics matter, so let me walk through them. Meta sold $25 billion of common stock at $625 a share, an offering it upsized from $22.5 billion before the ink was even dry. It sold another $12.5 billion of depositary shares at $50. And it plans a further program of up to $60 billion once a brand-new class of non-voting Class C shares (announced during last week's earnings release) begins trading, which Meta expects in the first quarter of 2027, with the timing and terms still to be set. That’s right–non-voting. Meta is asking investors for tens of billions of dollars and, for the biggest piece of it, offering no say in how it gets spent. And then came the fine print. NVIDIA–NVIDIA!--announced it will invest $3 billion in the offering, alongside an expanded partnership on Meta's Muse AI models and a commitment from Meta to deploy more NVIDIA infrastructure in its data centers, including its next-generation Vera Rubin systems. NVIDIA, AMD and Broadcom together signaled interest in up to $5 billion of Meta's Class A shares. Three chipmakers lining up to buy stock in one of their biggest customers. If somebody made a tombstone for this deal, they would need a bigger block of lucite.
Why would one of the greatest cash machines in corporate history–Meta–need to sell stock at all? I covered Meta's third quarter here last week, so I won't relitigate the whole thing, but one number deserves a second look. Meta burned $2.12 billion of cash in the third quarter–its first negative free cash flow in more than a decade. A year earlier, that same line was a positive $10.63 billion. The company has lifted the bottom of its 2026 capital spending range to $135 billion to $145 billion and has committed to roughly $825 billion of future spending, mostly on data centers and AI infrastructure. At the end of September, Meta held $82.45 billion of cash and marketable securities against $80.92 billion of long-term debt–essentially even. That is not a crisis. Meta is not running out of money. But it is a company that, for the first time in a very long time, is spending more than it makes, and it has already gone to the bond market for a record deal and to private credit for a $27 billion data center financing with Blue Owl last October. Debt first, private credit second, and now equity–and lots of it. When a company works its way through every window at the bank, it is worth asking what the line at the next window looks like.
Here is the part that would have caught my eye back in the days of that dusty cardboard box in Murray Hill, New Jersey (Lucent’s HQ at the time). There is nothing new about a supplier helping its customers pay for its products–it is called vendor financing, and it is as old as the department store charge card. What is new is the form. NVIDIA is not lending Meta money. It is buying a piece of Meta. And this is not a one-off. NVIDIA committed more than $40 billion to AI equity investments in just the first four months of this year, with $30 billion of that going to OpenAI, plus stakes across a long list of the AI labs and cloud operators that buy its chips. To be fair–and I want to be fair–Jensen Huang has called the "circular financing" critique ridiculous, arguing that these stakes are a small fraction of the capital his customers need and represent long-term conviction, not financial engineering. He has a point. Equity is not a loan. Nobody has to pay it back, there are no covenants to trip and no interest coming due in a downturn. If Meta's AI bets pay off, NVIDIA will have bought a slice of a winner. That is a legitimate investment thesis. But it is also true that when the money flows from the supplier to the customer and then right back to the supplier as purchase orders, it gets harder–much harder–to tell how much of the demand is organic and how much has been financed.
Um…I have seen this movie, and I remember the ending. In October 1998, Lucent signed a five-year agreement to supply Winstar, one of the fast-growing upstart phone and data carriers of that era, with broadband network equipment–and agreed to provide up to $2 billion in financing so Winstar could afford to buy it. Winstar was hardly alone. By the middle of 2000, Lucent had made about $7.7 billion of credit commitments to its customers and guaranteed about another $1 billion of their debt. Equipment orders were booming, revenue was booming, and the tombstones were piling up. Then the capital markets slammed shut on the upstart carriers. In April 2001, Winstar missed $75 million of interest payments, filed for bankruptcy, and sued Lucent for $10 billion, claiming Lucent had breached its financing agreement. Lucent called the suit frivolous and took heavy reserves against its Winstar loans. But one detail from that saga has stuck with me for twenty-five years. Winstar needed Lucent's money in order to pay back its creditors–and one of those creditors was…er, Lucent. The supplier's sales depended on the customer's financing, and the customer's financing depended on the supplier. When one domino wobbled, they all went.
Let me be clear about what is different this time, because the differences are real. Meta is not Winstar. Winstar was a debt-fueled startup with a business plan. Meta brought in more than $200 billion of revenue last year from an advertising business that reaches billions of people every day. NVIDIA is not Lucent circa 2000, either–it is buying equity in a cash-rich giant, not extending loans to fledglings. Anyone telling you that 2026 is a carbon copy of 2001 is selling something. But history rarely repeats itself perfectly, and the rhyme here is loud enough to hear from the back of the room. The suppliers are funding the customers. The customers are funding the buildout with every form of capital they can find. And the signal investors use to judge the whole cycle–demand for chips–is increasingly tangled up with the financing behind it.
The risk is not that Meta goes broke. The risk is that the AI trade is starting to grade its own homework. When chipmakers buy their customers' stock and those customers turn around and buy their chips, the order book that Wall Street celebrates every quarter becomes a little less of a measurement and a little more of an arrangement. So ask yourself a few questions before your next look at your portfolio. How much of the demand you are paying for is self-funding? If you own Meta, are you comfortable being diluted by a share class that does not even get a vote? What happens to the next $60 billion if the stock is lower when it is time to sell it? And if spending slows, where do the bond buyers, the private credit funds and the chipmakers holding equity end up standing in line? I don't know the answers yet. Neither does anyone else–and THAT is kind of the point.
That box of deal toys eventually went the way of most mementos–into storage, then a closet, then a basement, then ultimately–the landfill (to be honest I left them in my office when I left 🤣). Most of the companies sealed inside those little acrylic blocks no longer exist, and more than a few of the lenders printed in the fine print ended up as the biggest losers. I learned to read the small type the hard way. If somebody hands out tombstones for this deal, I suspect NVIDIA’s name will appear three times–once as the supplier, once as the partner, and once as the shareholder. I have plenty of desk space these days. I'm just not sure I want a new deal toy.
YESTERDAY’S MARKETS
Stocks closed higher on Monday as Anthropic’s IPO filing lifted AI shares, with the Dow Jones Industrial Average gaining 146 points to 52,361, the S&P 500 rising 0.70% and the Nasdaq Composite advancing 0.82%. Technology was the best-performing sector at 1.5%, and the Philadelphia Semiconductor Index rose 2.8% but remains down 12.2% for October. Tesla jumped 5.2% to its highest close in more than three months after Barclays upgraded the stock to overweight, while optical-component makers Lumentum and Coherent gained about 8% and 6%, respectively. Meta fell 1.9% after announcing plans to raise up to $95 billion in equity to fund its AI infrastructure. 🙃
NEXT UP
-
Durable Goods Orders (October 10th) are expected to have risen by 1.9% after slipping by -0.1% in September.
-
FHFA House Price Index (August) may have gone up by 0.2% after climbing by 0.3% in July.
-
Conference Consumer Confidence (October) may have slipped to 81.0 from 81.9.
-
New Home Sales (September) probably fell by -4.5% after climbing by 6.4% in the prior period.
-
Important earnings this morning: Freeport-McMoRan, Hilton Worldwide, Ares Capital, Royal Caribbean, Invesco, Johnson Controls, Coca-Cola, UPS, PayPal, American Tower, SoFi, Sherwin-Williams, HCA Healthcare, Corning, Eccolab, Boeing, Waste Management, Robinhood, ONEOK, Visa, Seagate, Caesars Entertainment, and Baker Hughes.
 service@siebert.com
 Siebert Financial (800)872-0444