
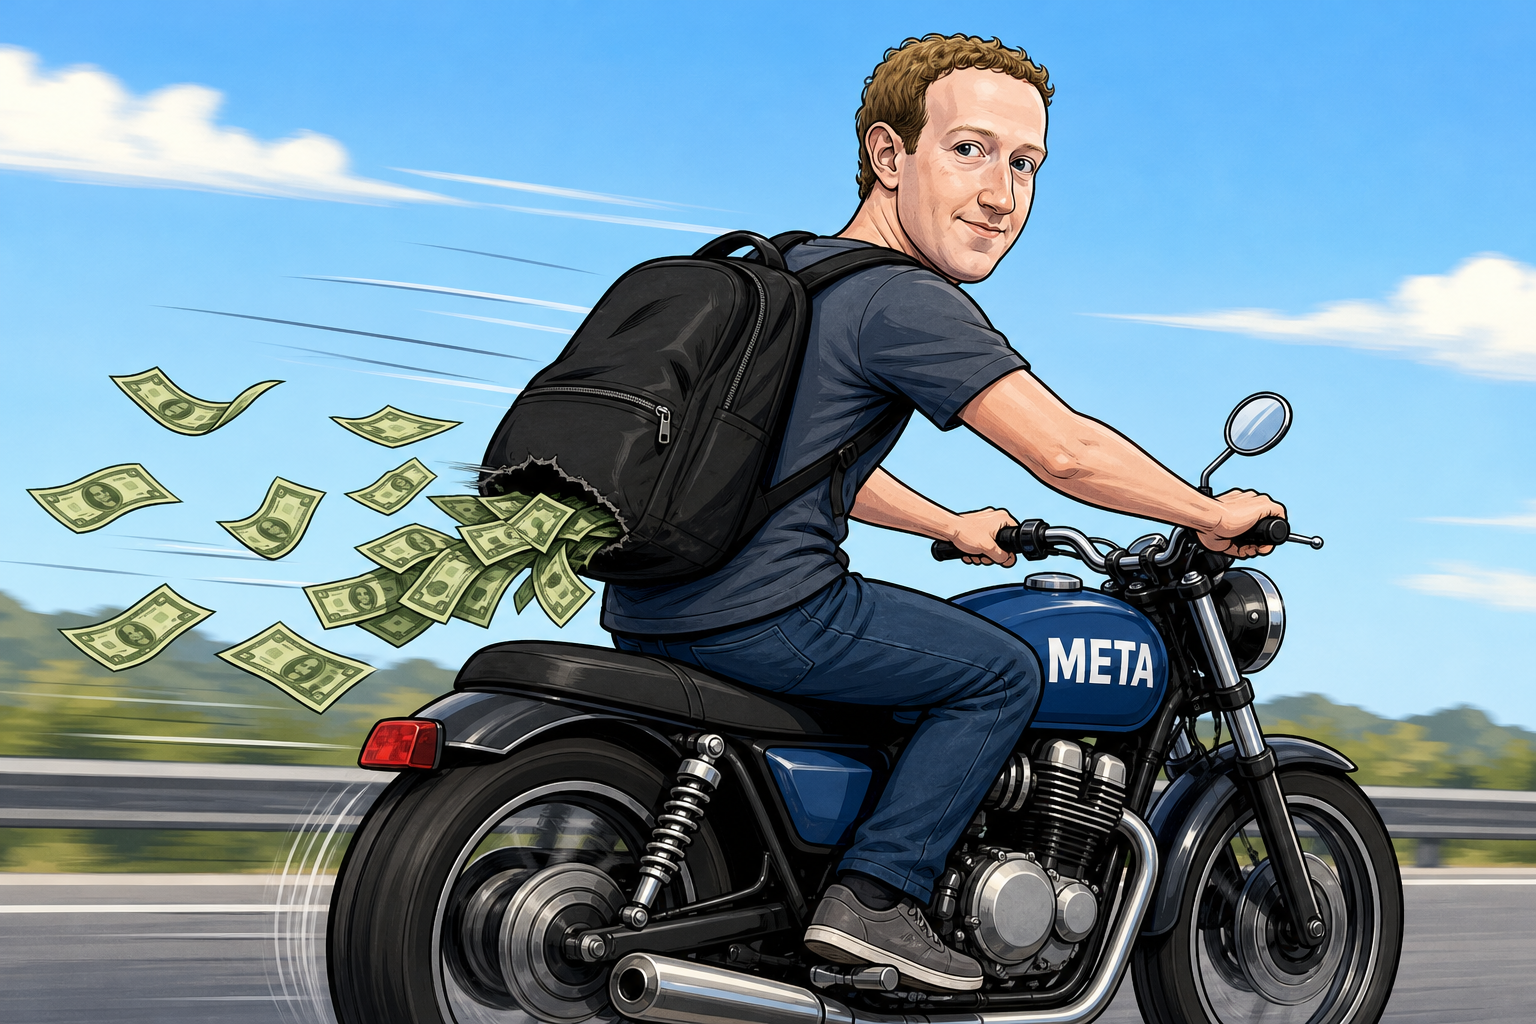
Meta generated $32.79 billion in operating cash but spent $34.91 billion on capital projects. Is the AI investment cycle outrunning cash flow?
KEY TAKEAWAYS
-
Meta's core business remains exceptionally strong, but AI spending is consuming its cash generation. Third-quarter revenue reached a record $64.6 billion, up 26%, while free cash flow turned negative at $2.12 billion as capital expenditures exceeded operating cash flow.
-
Meta's capital expenditure guidance has become progressively more aggressive throughout 2026. The company's spending floor increased from $115 billion in January to $135 billion in October, implying approximately $49 billion in fourth-quarter expenditures to meet even the low end of guidance.
-
Meta introduced a new class of nonvoting shares that could expand its financing flexibility. The Class C shares will allow the company to raise capital, compensate employees, and pursue acquisitions without surrendering additional voting control.
-
Tesla pursued a different near-term spending strategy, reducing capital expenditures and generating positive free cash flow. However, management indicated that substantial spending remains ahead, suggesting that the reduction represents a delay rather than a permanent change in investment ambitions.
-
Investors are increasingly evaluating AI companies based on cash generation rather than revenue growth alone. Meta's record results failed to sustain a positive market reaction, signaling growing sensitivity to spending commitments, capital intensity, and the timing of investment returns.
MY HOT TAKES
-
Meta's problem isn't its advertising business; it's the growing distance between revenue growth and capital spending. A company with record sales and negative free cash flow is demonstrating that even an exceptionally profitable operating model can struggle to finance an increasingly capital-intensive AI strategy.
-
Meta's rising capital expenditure floor is more revealing than its unchanged spending ceiling. When management repeatedly raises the minimum while leaving the maximum untouched, the upper end begins to look less like a worst-case scenario and more like the actual spending target.
-
The creation of nonvoting shares is a significant strategic development that investors shouldn't overlook. Introducing a new financing instrument while free cash flow is negative suggests management wants greater financial flexibility without weakening founder control, raising important questions about future shareholder economics.
-
Tesla's spending reductions represent a change in timing rather than a retreat from its capital-intensive ambitions. Near-term free cash flow improves, but management's projections for much greater expenditures in 2028 suggest that the financial challenges confronting Meta could eventually confront Tesla as well.
-
Wall Street is entering a new phase of the AI investment cycle in which cash-flow discipline matters as much as technological ambition. Companies that cannot demonstrate a credible relationship between spending, revenue growth, and eventual cash generation risk losing investor support, regardless of how impressive their earnings headlines appear.
-
You can quote me: "Beating on revenue is no longer enough. Investors want to see the cash–and they want to see it on time."
Show me the money–the cash. I like repetition. I find comfort in it. My wife says that there is a diagnosis for that–maybe, but it works for me, so I stick to it–and I repeat it. My mornings start the same way–espresso in hand, the pile of rubber-banded newspapers that used to land at my door has given way to digital versions on an iPad on my lap, local New York TV news murmuring in the background, mostly for two things: the weather and the subway delays (one of which I can do something about 🤣). Over the years I’ve noticed something about forecasters. When they’re unsure, they give you a range–“highs between 58 and 64.” When the storm is real, the range doesn’t widen. The LOW end just keeps creeping up, forecast after forecast, until everyone finally reaches for the umbrella. Last night Meta gave its fourth spending forecast of the year. The high end hasn’t budged since spring. The low end? It has gone up every…single…time. Somebody, please pass me an umbrella.
In yesterday morning’s note, I promised I’d ask Meta the very same questions I asked SpaceX. A promise is a promise. And this one matters more than usual, because Meta was the first of the AI heavyweights to step up to the plate this earnings season. These first few AI-related earnings announcements will set the mood for the rest. If the early reports convince investors that the spending is paying off, everyone who follows gets the benefit of the doubt. If they don’t, every report after them gets read with a red-hued magnifying glass. So, let me start with what went right, because plenty did. Revenue hit a record $64.6 billion, up 26% from a year ago and comfortably ahead of the $63.37 billion Wall Street expected. Management guided fourth-quarter revenue to $73 billion to $76 billion. The headline earnings number looked ugly–$3.83 per share–but that was a legal bill, not a business problem. Meta booked a $9.89 billion charge tied to its August settlement with 52 state attorneys general over teen mental health litigation (a deal calling for payments of up to roughly $18.59 billion in total). Strip it out, and earnings would have been $7.40 per share. Importantly, the ad machine is humming. That was never the question.
The question was the cash–quite right–it always starts there for me. Free cash flow (the cash a company has left after paying for the buildings, chips, and data centers that keep it running–the money that can actually fund dividends, buybacks, or a…um, rainy day) came in at NEGATIVE $2.12 billion. Meta generated $32.79 billion of cash from operations in the quarter and spent $34.91 billion on capital expenditures. Read that again. 👈👀 The spending outran the cash coming in the door. A year ago, the same quarter produced $10.63 billion of free cash flow. Now look at the path this year: roughly $12.4 billion in the first quarter, $784 million in the second, and below zero in the third. That’s not a dip–that’s a trend line with a direction. The cash pile tells the same story. Cash and marketable securities fell to $82.45 billion, from $90.26 billion just three months earlier. And here’s a detail most people skimmed right past: Meta still paid out $1.36 billion in dividends during a quarter when its free cash flow was below zero. That’s not a crisis–but it does mean the dividend check came out of savings, not out of the quarter’s earnings power. Let me be fair: $82 billion is an enormous cushion, and Meta is nowhere near financial distress. But a company that once paid for its ambitions out of its weekly paycheck is now dipping into savings–something I repeatedly warn my kids about. 😉 That’s a different company than the one many investors think they own.
Which is where my weather forecaster comes back in. When Meta first gave 2026 guidance in January, it expected capital expenditures of $115 billion to $135 billion. In April, $125 billion to $145 billion. In July, $130 billion to $145 billion. Last night, $135 billion to $145 billion. The ceiling has been parked at $145 billion since spring. The floor has climbed every single quarter. Here’s the part that didn’t make the headlines. Through the first three quarters, Meta has spent roughly $86 billion. To hit even the LOW end of the new range, it would need to spend about $49 billion in the fourth quarter alone–roughly 40% more than the record $34.91 billion it just spent. In my experience, when the bottom of a range keeps rising and the top never moves, the most honest number in the forecast is the top. That isn’t a forecast range, my friends. That’s a ratchet.
And that brings me to the announcement that, in my view, deserves far more attention than the earnings. Meta’s board approved a brand-new class of publicly listed stock–Class C common shares–that carries no voting rights at all. Effective January 19, 2027, every shareholder will receive one Class C share for each Class A or Class B share they already own. For the market price, it works much like a two-for-one stock split. For control, it changes nothing–no shareholder gains or loses a single vote, and the founder’s ten-vote Class B shares stay exactly where they are. Think of it as a seat at the dinner table with a full plate–but no say in what’s for dinner. Meta says it wants the new shares available for raising capital, paying employees, and making acquisitions. And the plan was approved by written shareholder consent–so the shares with no vote never needed a vote from the minority holders who will receive them. 😉 Is this sinister? Not necessarily. Plenty of companies run multiple share classes, and nobody is being diluted today. But think about what it actually means. Meta just built itself a printing press for a new currency–one it can use to pay engineers, buy companies, or raise money–without ever loosening its grip on the steering wheel. A company that can pay for its dreams doesn’t need to print a new currency. That Meta built the press in the very quarter its free cash flow turned negative tells me management is thinking hard about how the bills get paid, too.
Tesla, reporting the same evening, chose the opposite road. It spent $4.7 billion on capital expenditures in the third quarter–far below the roughly $7.5 billion analysts expected–and cut its full-year 2026 forecast to about $20 billion from $25 billion. The result was a surprise positive free cash flow quarter of roughly $1.5 billion, and management said it will fund its spending from operating cash flow. Prudent? Absolutely. But read the fine print–you know I love the fine print. Elon Musk said spending becomes more meaningful next year and reaches the tens of billions in 2028. That isn’t a retreat. It’s a… … …postponement. Meanwhile, Tesla and SpaceX–yesterday’s bigger-boat 🦈 company–have each formed special committees to explore a merger. The self-funder may soon be married to the biggest spender in the room. And how did investors reward the discipline? Tesla shares fell more than 3% after hours. Damned if you spend, damned if you don’t. My read: the market isn’t asking companies to spend less. It’s asking for proof that the revenue shows up on the same schedule as the bills–a theme I have been repeating…and repeating…and, er, you know.
And the mood I mentioned? It’s already being set. Meta’s early after-hours pop faded overnight, Nasdaq futures were down about 1.8% this morning, and global stocks retreated right along with them. SpaceX slid 2.3% and Super Micro fell 4.7% in premarket trading as investors stopped celebrating earnings and started tallying the cost of the buildout. A rebound in oil–Brent back above $110 a barrel after a drone strike near a Saudi oilfield–isn’t helping anyone’s appetite. Think about what that means. Meta delivered a RECORD quarter and still couldn’t lift the room. For every AI heavyweight still waiting to report, the bar just moved higher. Beating on revenue is no longer enough. Investors want to see the cash–and they want to see it on time.
So, as promised, here are the questions I’m asking–the same ones I asked of SpaceX, now with Meta’s name on them. Is revenue growing faster than spending? Revenue grew 26% this quarter, while this year’s spending plan is roughly DOUBLE last year’s $72 billion. If ad growth cools even modestly, how long before negative free cash flow stops being a one-quarter event? Who owns the bottlenecks–chips, power, cooling–and how much of Meta’s spending simply flows to them? And one every shareholder should ask themselves: what does owning a piece of this company look like five years from now if a growing share of the stock comes with no vote at all? I won’t answer those for you. But you should ask them.
Which brings me back to my morning forecaster. Here’s the thing about a low that keeps creeping up–eventually the forecast stops being a forecast and becomes the weather. Meta’s forecast was verified last night. It’s raining cash out of the cash-flow statement, and the company quietly built itself an umbrella with no voting rights attached. Tesla, meanwhile, decided to stay indoors–at least until 2028. Tomorrow morning, espresso in hand, I’ll be checking two forecasts: one for New York City, and one for Silicon Valley. To be fair to my New York forecaster, she has been known to lower the low every now and then. I’m still waiting for Silicon Valley to try it. ☔😉
YESTERDAY’S MARKETS
Stocks rose for a third straight session yesterday, led by technology shares. The Dow Jones Industrial Average gained 360 points, or 0.7%, to 52,856, the S&P 500 rose 0.6%, the Nasdaq Composite added 1.1%, and the small-cap Russell 2000 gained 0.3%. The 10-year Treasury yield was little changed at about 5.13%. WTI crude settled down 0.7% at $97.15 a barrel, while Brent was essentially flat at $108.82.
NEXT UP
-
Initial Jobless Claims (October 17) is expected to come in at 200k, a tick higher from last week’s 199k claims.
-
Leading Economic Index (September) may have slipped by -0.1% for a second straight month.
-
Important earnings today: Dow Inc, Honeywell, PG&E, Lockheed Martin, Valero Energy, PulteGroup, Quest Diagnostics, Tractor Supply, Comcast, American Airlines, Procter & Gamble, Blackstone, Union Pacific, VeriSign, NEwmont, Deckers Outdoors, Western Digital, and Comfort Systems.
 service@siebert.com
 Siebert Financial (800)872-0444