

JPMorgan’s trading miss grabbed headlines, but its reserve build and shrinking appetite for risky loans may tell investors far more about what comes next.
KEY TAKEAWAYS
-
JPMorgan finally missed expectations after eight consecutive beats, but the weakness came primarily from trading rather than lending. Fixed-income trading disappointed while equities performed better, making this look more like an earnings wobble than deterioration in the bank’s core franchise.
-
The underlying banking business remains remarkably healthy. Net interest income beat expectations, loans and deposits were strong, and consumers continued spending despite high energy costs and elevated interest rates.
-
Consumer credit has not yet cracked at JPMorgan. Card charge-offs declined, total net charge-offs came in below expectations, and late-stage delinquencies improved—but JPMorgan’s relatively affluent customer base makes it an imperfect proxy for financially stressed households.
-
JPMorgan is preparing for conditions to deteriorate even though current credit performance remains strong. The bank provisioned roughly $539 million more for future credit losses than it actually charged off during the quarter.
-
The bigger potential warning is developing outside traditional banking. Banks are becoming more selective about AI-related lending while private-credit vehicles face investor redemption pressure, creating a potentially important collision between illiquid assets and demands for liquidity.
MY HOT TAKES
-
The earnings miss itself is mostly noise. A weak bond-trading quarter bothers me far less than deterioration in loans, deposits or consumer credit would have.
-
The reserve build is much more interesting than the headline earnings number. Banks are professional worriers, and JPMorgan is putting additional money aside while its actual credit statistics remain healthy.
-
Credit tightening usually begins quietly. Sophisticated lenders reducing exposure and investors demanding additional yield are precisely the kinds of incremental changes I watch before stress becomes obvious.
-
Private credit has a structural liquidity mismatch investors may underestimate. Redemption gates are functioning as designed, but that does not make them irrelevant when investors simultaneously want cash and lenders become less willing to provide leverage.
-
The next important signal comes from private-credit reporting. I want to see liquidity, leverage, redemption requests, funding costs and whether banks are becoming more restrictive with the credit facilities underpinning the industry.
-
You can quote me: “And by the way, when a bank boss or central banker says ‘elevated asset prices,’ they are referring to possibly over-valued stocks.”
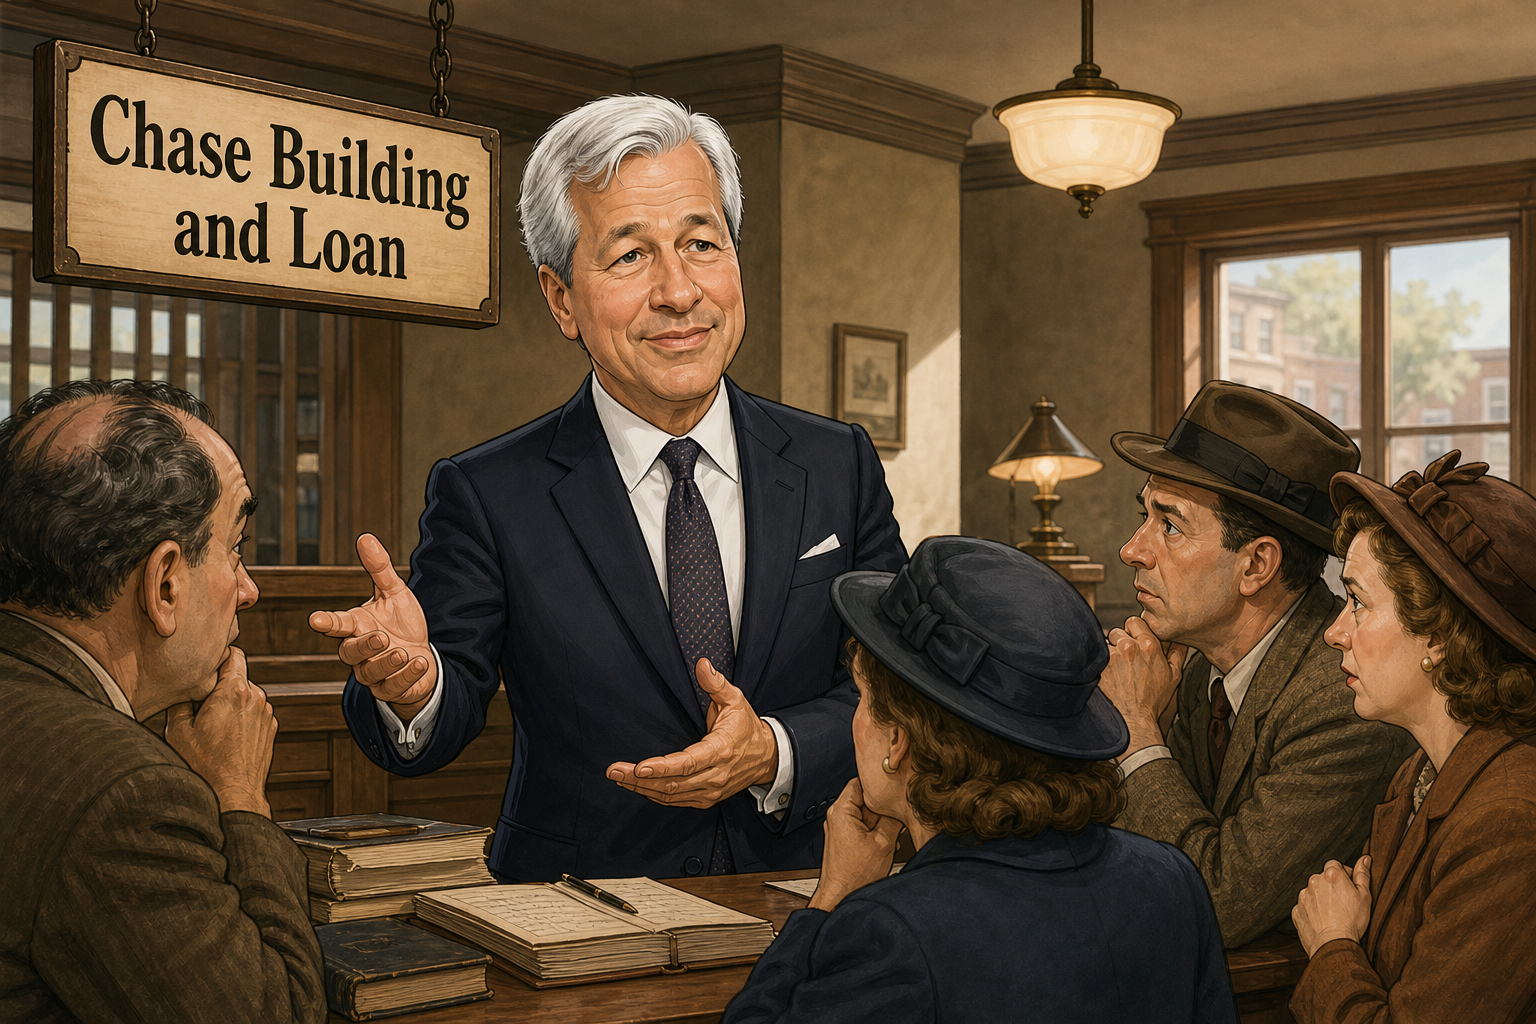
Clipped wings. Ok, I am sorry to have to be “the guy” to do this to you, but this train is coming regardless, and I figured, may as well get ahead of it. Besides, I have caught a few holiday ads on TV already. I just couldn’t resist–I’m sorry. I watch It’s a Wonderful Life every December–EVERY December–and while everyone else waits for the bell on the tree and the angel getting his wings, I wait for the bank run. A crowd of frightened depositors pushes into the Bailey Building and Loan demanding their money, and George Bailey–Jimmy Stewart at his absolute best–climbs behind the counter and explains that the money isn’t sitting in a vault in the back. It’s in Joe’s house. It’s in the Kennedy house. It’s in Mrs. Macklin’s house. He lent it to them so they could build. In almost four decades in this business, I have never heard maturity transformation (the fancy Wall Street term for borrowing short-term and lending long-term) explained better–not in a textbook, not on a trading floor, and CERTAINLY not on an earnings call. A bank is a promise to give you your money back–just not all of it, not all at once, and not to everyone on the same afternoon. I bring this up because this morning was all about earnings calls, and George’s lesson is about to matter in a corner of the market most investors never watch.
JPMorgan Chase kicked off bank earnings season before the bell, alongside Goldman Sachs, Wells Fargo and Citigroup, with Bank of America, Morgan Stanley and BlackRock to follow tomorrow. The banks always go first, and for good reason. They sit at the center of…er, everything–the paycheck in your checking account, the card you swiped at the pump, the loan a private equity firm used to buy a company you’ve never heard of. If you want to know how the economy is really doing, ask the people who are owed money by everybody.
And this morning, the people who are owed money by everybody came up short. JPMorgan earned an adjusted $5.57 a share against the $5.90 Wall Street expected, on adjusted revenue of $50.91 billion versus $51.37 billion. Net profit was $15.31 billion. Return on equity–the measure of how much profit a bank squeezes out of its shareholders’ capital–came in at 17% against expectations of 17.8%. This is the bank that had beaten the consensus estimate eight quarters running. Eight! The shares slipped on the news, and I’m not surprised, because the market doesn’t price the number, it prices the CHANGE in the story. And the story coming in was perfection. Bank stocks had been nervous for weeks, the KBW Bank ETF sitting around 12% below its mid-August high, and investors were waiting for a reason. JPMorgan just gave them a small one.
But–and this is a big but–WHERE the miss came from matters far more than the miss itself. The culprit was the bond trading desk. Fixed-income trading revenue (what Wall Street calls FICC–fixed income, currencies and commodities) came in at $5.37 billion against an estimate of $6 billion, down 4% from a year ago. It was the first decline in that business in more than two years. Equities trading actually beat, at $4.95 billion versus $4.47 billion expected, which left total trading revenue at $10.3 billion, really a hair below the $10.5 billion the Street was looking for. Investment banking also fell short, at $3.10 billion against $3.27 billion. Now think about what that means. Trading revenue is the most volatile line on a bank’s income statement–it depends on how much clients reposition, how violently markets swing, and how good the desks are at catching the waves. A soft quarter in bond trading is disappointing. It is NOT a crack in the foundation. Before I write off the leader of the pack, I’ll take a bad quarter at the casino over a bad quarter at the loan desk every single time.
And the loan desk was fine–better than fine, actually. Net interest income (what a bank earns on its loans minus what it pays depositors) came in at $27.15 billion, beating the $26.87 billion estimate. Strip out the trading operation, and NII was $24.7 billion, up 6%. Loans reached $1.58 trillion and deposits $2.78 trillion, both above expectations. That last number deserves a pause. With the 10-year Treasury yield hitting 5.31% earlier this month–levels we haven’t seen since before the financial crisis–you might expect depositors to be fleeing to money market funds and Treasury bills. They aren’t. Not at JPMorgan, anyway.
Then there’s the consumer, and for this I always read the card book. Debit and credit card sales volume rose 10% from a year ago. The card charge-off rate (the share of balances written off as uncollectible) fell to 2.91% from 3.34% last quarter. Total net charge-offs were $2.20 billion, well below the $2.48 billion the Street feared, and the most recent delinquency data showed late-stage delinquencies actually ticking down. With diesel averaging $6.28 a gallon just last week, I expected the household to look more bruised than this. It doesn’t–at least not the household that banks at Chase. And that caveat matters. JPMorgan’s customer base skews toward borrowers with better credit, so this is a read on the top of the K, not the bottom. The stress shows up first at subprime lenders and smaller banks, and I’ll be watching them as their reports come in.
Here is the detail I find most telling. Even with charge-offs falling, JPMorgan set aside $2.74 billion for future losses; that’s about $539 million MORE than it actually wrote off. That’s called a reserve build, and it’s the banker’s version of carrying an umbrella on a sunny day. 😉 Jamie Dimon called the U.S. economy “solid,” citing strong business investment and consumer spending. In the same breath, he flagged large fiscal deficits, sticky inflation, elevated asset prices, rising interest rates and geopolitical conditions. Translation–things are good, and he is preparing for them not to stay that way. And by the way, when a bank boss or central banker says “elevated asset prices,” they are referring to possibly overvalued stocks.
Which brings me back to George Bailey, and to the story I think most investors will miss today. Buried in this morning’s headlines, JPMorgan and Goldman Sachs moved to limit their exposure on a $5 billion loan for an AI infrastructure startup called Volta Infrastructure Holdings, as investors demanded higher yields to own AI-linked debt. Read that again. 👈👀 Two of the most sophisticated lenders on the planet looked at a loan and decided they’d rather hold less of it–and the buyers on the other side wanted to be paid more for taking the risk. That is what the early stages of a credit tightening look like. Not a crash. A shrug, a raised eyebrow, and a higher price.
And it’s happening against the backdrop of private credit, which has spent this year living through its own Building and Loan moment. Private credit funds–and the business development companies, or BDCs (investment vehicles that act like mini-banks, lending to mid-sized private companies), that bring them to everyday investors–have been hit with wave after wave of withdrawal requests. As of early October, seven of ten non-traded private credit BDCs tracked by one industry monitor had prorated their most recent buyback offers, paying out somewhere between 13% and 48% of what investors asked for. Earlier this year, non-listed BDCs handed back more money than they raised in a quarter for the first time. Those withdrawal limits are not a malfunction, they are the design. Just like George’s depositors, BDC investors own claims on money that is out in the world, lent to companies that can’t simply pay it back on demand. But many of those funds borrow from banks like JPMorgan to juice their returns–called back credit facilities. When the biggest banks start trimming exposure and demanding more yield, the lenders who depend on them feel it first. Several of the largest private credit funds report at the end of the month, with Blackstone’s and Apollo’s flagship funds following in early November.
So what should investors be asking themselves this week? Was this morning’s miss a one-off wobble on the trading floor, or the start of a slowdown in the deal-making machine? Why is a bank with falling charge-offs building reserves–and will Bank of America and Morgan Stanley do the same tomorrow? And if the strongest lender in the country is getting choosier about who it lends to, what does that mean for the funds that depend on borrowed money to pay their investors? None of these have one-line answers. That’s the point.
There’s a moment in the film that I think gets overlooked. George and Mary hand over their own honeymoon money–$2000–to get the Building and Loan through to closing time. The run ended not because the money was in the vault, but because somebody had cash on hand when everyone came knocking at once. This morning, JPMorgan missed its numbers and quietly added $539 million to its honeymoon fund anyway. I’d pay attention to that. In a few weeks, the private credit funds will show us how much honeymoon money they have left–and that is THE report I’ll be reading most closely. Oh, and if you come to visit us, New York’s famous Rockefeller Center skating rink opened for business this past weekend–so it’s not just me. 😝
YESTERDAY’S MARKETS
Stocks finished mixed yesterday to open a busy week, with the market hovering near the all-time high it set last week. The S&P 500 slipped 0.1%, the Dow Jones Industrial Average rose 195 points, or 0.4%, to 51,850, while the Nasdaq Composite fell 0.4%. Brent crude rose 1.8% to $106.65 a barrel, and the U.S. bond market was closed for Columbus Day.
NEXT UP
-
NFIB Small Business Optimism (September) came in lighter than expected at 97.9, lower than last month’s 98.7.
-
Existing Home Sales (September) may have slipped by -0.8% after falling by -2.0% in August.
-
Fed speakers today: Waller, Goolsbee, Barkin, and Collins.
-
Important earnings today: UnitedHealth, Albertsons, J&J, Wells Fargo, Domino’s Pizza, JPMorgan Chase, Goldman Sachs, and Citigroup.
 service@siebert.com
 Siebert Financial (800)872-0444