

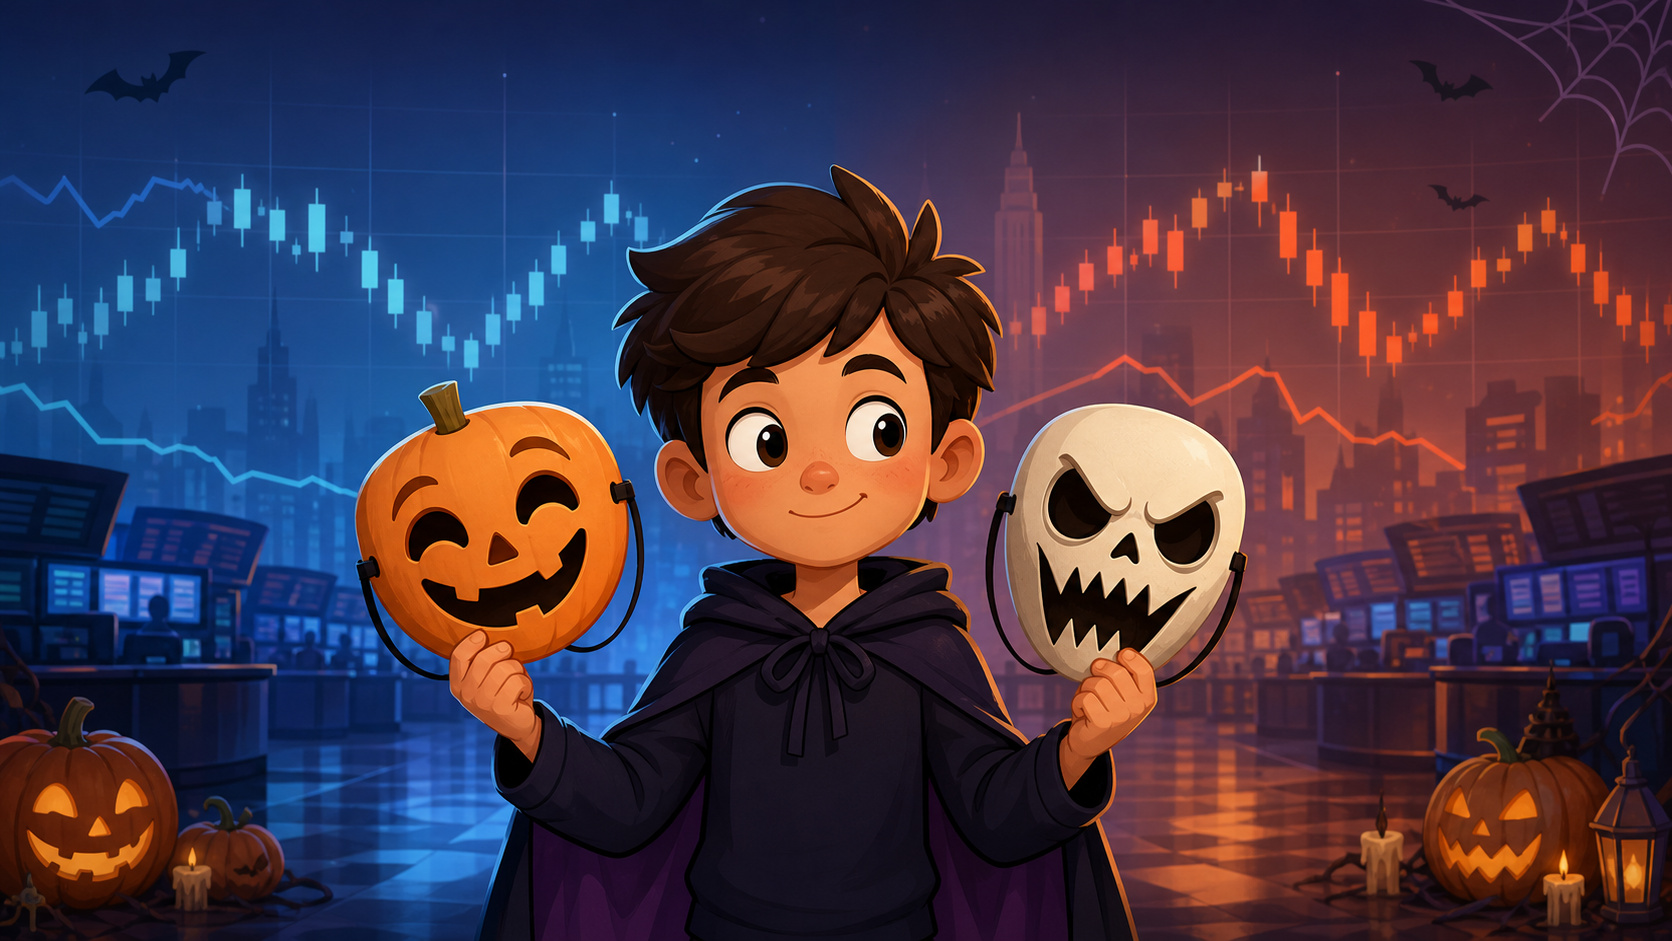
Wall Street hates uncertainty, not political parties. Discover what 120 years of market history reveals about midterm elections and stock returns.
KEY TAKEAWAYS
-
Post-midterm stock market returns have historically been strong. Since 1946, the S&P 500 has advanced in the 12 months following every midterm election, with an average return of approximately 15%.
-
The historical advantage is less convincing over shorter periods. Since 1874, stocks have averaged a gain of just 0.5% in the month following midterms, with positive returns occurring only 55% of the time.
-
The S&P 500 has experienced five months of essentially flat performance. Friday's closing level of 7,580.07 was just one cent above its May 29 close of 7,580.06, despite significant volatility and a record high in October.
-
Monetary policy remains a potential headwind for equities. The Federal Reserve held rates at 3.75%–4.00% last Wednesday in a 10–2 decision, with both dissenting members favoring an increase.
-
Corporate earnings and economic data will compete with the elections for investors' attention. Apple, Palantir, and AMD report earnings this week, while October's employment report is scheduled for Friday morning.
MY HOT TAKES
-
Markets don't favor political parties; they favor predictability. The removal of election uncertainty may ultimately prove more important to investors than which party controls Congress.
-
The 20-for-20 post-midterm winning streak is compelling, but it is not a trading strategy. Historical patterns deserve consideration, but twenty observations cannot overcome weak fundamentals or excessive valuations.
-
Artificial intelligence spending is a bigger immediate threat to stocks than the midterm elections. Investors are increasingly demanding evidence that enormous AI capital expenditures will generate returns that justify their cost.
-
This market is entering the midterms from an unusually high altitude. With valuations elevated and the S&P 500 already up more than 10% this year, the conditions supporting previous post-election rallies may not be present.
-
The biggest portfolio mistake this week may be confusing a political opinion with an investment thesis. Investors should spend less time predicting election winners and more time examining their exposure to crowded AI trades, earnings risk, and monetary policy.
-
You can quote me: “Wall Street does not hate any particular party. What the market does hate is NOT KNOWING.”
Trick or treat. In the US, this past Saturday was Halloween, and anyone who has ever manned the candy bowl knows the hardest part of the night is not the candy–it’s the doorbell. You never know when it’s going to ring, and you NEVER know who’s on the other side. A pint-sized astronaut with a helmet two sizes too big. A princess who has clearly been coached to say “thank you” and forgets halfway through. Perhaps, a gaggle of teenagers who decided that a hoodie and a bored expression counts as a costume (it does not). Every time I opened that door, I had a split second of guessing–trick or treat, sweet kid or wise guy—and the mask told me absolutely nothing. That’s the genius of a mask. It is engineered to hide the one piece of information you want most. By the end of the night the bowl was nearly empty, the doorbell had gone quiet, and I was left with a handful of assorted candy (thankfully all my favorites 😋) that nobody touched.
Thinking about Halloween, it dawned on me that markets wear masks too, and there is no costume Wall Street wears more reliably than the one it puts on before a midterm election. Tomorrow, Americans head to the polls to elect all 435 members of the House, 35 Senators and 36 governors. I am not going to tell you who is going to win–that is not my job, and frankly, it is not the market’s job either. Here is what I will tell you: Wall Street does not hate any particular party. What the market does hate is NOT KNOWING. Uncertainty is the costume, and investors have been answering the door and guessing for months.
History is surprisingly clear about how that costume affects returns. Looking back to 1900 (using the Dow until 1929 and the S&P 500 after that), we note that the S&P 500 averaged just a 2.9% return in the 12 months leading up to a midterm, versus 8.9% for all years. Then the mask comes off–and the average return in the 12 months after the election jumps to 12.4%. Narrow the lens to the postwar era and the pattern gets even more striking. Measured from the last close before Election Day to one year later, the S&P 500 has been higher after every single midterm from 1946 through 2022–20 for 20–with an average gain of roughly 15%. Twenty for twenty! Through wars, oil shocks, recessions and one party or another losing control of Congress. The weakest showing since 1950 was the year after the 1986 midterms, which gained just 2%--and that window included Black Monday in October 1987, the single worst day in the history of the market. The worst day EVER, and the market still finished better in the year ahead.
Why does this happen? I have a few thoughts. The first is the obvious one: once the votes are counted, the uncertainty premium (the extra return investors demand for living with the unknown) starts to evaporate, and capital that was sitting on the sidelines–waiting to see who rings the doorbell–walks back in. The second is gridlock. Midterms frequently produce a divided government, and a divided government is a government that has a hard time doing anything dramatic. Markets don’t need Washington to do great things; they mostly need Washington not to do surprising ones. The third is the calendar. The year after a midterm is the year before a presidential election, and every administration on record has had a keen interest in a strong economy heading into that one.
Now, before you rush out and buy a bag of full-size candy bars, let me be the guy who reads the label. Twenty observations is a pattern, not a law of physics. The same analyst that produced those pre- and post-midterm numbers ran the statistics and could not prove that pre-midterm returns since 1980 are meaningfully different from other years. Remove just one year with obvious outside drivers–1974, 2002 or 2022–and the effect gets even harder to distinguish from noise. Small samples, lots of confounding factors (economic forces that have nothing to do with elections). And the treats do not arrive the morning after, either. Going all the way back to 1874, the S&P 500 has averaged a gain of just 0.5% in the month following a midterm, and it has been positive only 55% of the time. That’s a coin flip–a COIN FLIP. If the pattern pays off at all, it pays the patient.
Which brings me to this year’s costume, because it is a strange one. The S&P 500 closed Friday at 7,580.07. On May 29, it closed at 7,580.06. Five months of headlines, a Fed rate hike, a record high on October 6, an oil spike, an AI frenzy–and the index moved exactly one penny. One penny! That is a market wearing a mask so convincing it even fooled itself. And Friday was no gentle way to end the month—the S&P 500 fell 1.82%, its worst day since June 5 while the Nasdaq dropped 2.86%.
You might be tempted to file all of that under “pre-midterm jitters.” I wouldn’t. Look at what actually rang the doorbell on Friday. Intel delivered weak guidance and suffered one of the worst days in its history, setting off a chip rout around the world. Amazon got punished for heavy AI spending without the cash flow to match it. That selling had nothing to do with ballots—and EVERYTHING to do with whether the hundreds of billions being poured into artificial intelligence will ever earn a return worth the price of admission. The election may be the costume, but AI CAPEX is the face underneath it.
That is why I would not simply lean on the 20-for-20 streak this time around. There are at least three wrinkles that make 2026 different from your average midterm. The first is valuation. Stocks are not cheap, and the S&P 500 is still up about 10.7% for the year even after Friday’s beating. History’s post-midterm rallies tended to launch from depressed levels–the average gain from the lowest close of a midterm year to one year later has been north of 30%. We are not launching from depressed levels. We are launching from a market that has gone nowhere at a very high altitude.
The second wrinkle is the Fed. Last Wednesday, the Federal Reserve held its benchmark rate at 3.75% to 4.00% in a 10-2 vote, and both dissenters wanted a hike. Right after the decision, futures were pricing in a high probability of a quarter-point increase at the December meeting. A Fed that is leaning toward tightening is not the kind of tailwind post-midterm rallies usually enjoy. But here is the counterpoint, and it is a good one–2022. That year the Fed was hiking aggressively, the S&P 500 suffered a 25.4% drawdown heading into the midterms, and the index still gained 13.6% in the 12 months after the vote. A hawkish Fed alone has not been enough to break the streak.
The third wrinkle is the one I keep coming back to: earnings. The ballots get counted Tuesday night, but the earnings get counted all week. Apple and Palantir report after the bell today, AMD is on deck, and the October jobs report lands Friday morning at 8:30 AM Wall Street Time. If the AI story cracks further this week, no election result is going to paper over it. If it holds, the post-midterm pattern has a fighting chance of doing what it has always done.
So rather than tell you what to do, let me hand you a few questions worth asking yourself before the doorbell rings tomorrow night. Is my portfolio built for the 12 months after the election, or the 12 hours after it? Am I about to make a political bet and call it an investment decision? Over the last five months the S&P 500 went nowhere while the average stock did much better than the index–do I actually know what I own, and how much of it is riding on the same handful of AI names that dragged October down? And if the market does get a post-election pop, will I chase it, or will I remember that the first month after a midterm has historically been a coin toss?
Futures are pointing to a higher open this morning, up by about half a percent for the S&P 500 and closer to a full percent for the Nasdaq 100, as the AI names catch their breath and oil pulls back. Enjoy it. Just don’t mistake a Monday bounce for the unmasking. That comes later–some races may take days to call, and the new Congress doesn’t even take office until January.
When the last trick-or-treater left on Saturday, I stood in the doorway looking at what was left in the bowl. History says the treats eventually show up after a midterm–just rarely on the first night, and never for the people who slam the door. And if Wednesday hands us a trick instead? Well, there’s always that leftover candy. I am keeping the bowl–just in case. 🤣
FRIDAY’S MARKETS
Stocks closed out October with a thud on Friday as a fresh wave of AI spending worries hit technology shares. The S&P 500 fell 1.82%, its worst session since June 5. The Nasdaq dropped 2.86%, and the Russell 2000 lost 1.66%. The Dow Jones Industrial Average shed 572 points to close at 51,770. The damage started with Intel, which plunged after delivering weak guidance. Amazon also came under pressure as investors balked at heavy AI capital spending without the cash flow to match. Beneath the surface, the average stock held up far better than the index, with the equal-weight S&P 500 ETF down just 0.79%. The 10-year Treasury yield fell 4 basis points to 4.94%, and Brent crude rose 2.37% to $113.43.
NEXT UP
-
ISM Manufacturing (October) is expected to come in at 54.5, same as September.
-
ISM Prices Paid (October) which will be closely watched by the Fed is expected to pull back slightly 77.2 from 77.9.
-
Construction Spending (September) may have climbed by 0.3% after gaining 0.9% in the prior period.
-
Chicago Fed’s Austan Goolsbee will speak today.
-
Important earnings today: Estee Lauder, Marriott International, IDEXX Labs, Lumentum, Fox Corp, Clorox, Lattice Semiconductor, ON Semiconductor, Apple, Vertex Pharma, Diamondback Energy, Realty Income, Williams, SBA Communications, Match Group, Roku, and Palantir.
 service@siebert.com
 Siebert Financial (800)872-0444